Earned Value Consulting

Earned Value Consulting is support services that an expert in Earned Value Management (EVM) provides to an organization to help them implement an Earned Value Management System (EVMS). EVM consulting services may be offered by organizations that have certified Earned Value professionals on staff, or by service providers who have been trained in EVM and can offer advisory or implementation services.

For a full description of what Earned Value Consulting is and who it is for, see our Knowledge Base article: https://www.humphreys-assoc.com/evms/earned-value-consulting-ta-a-252.html

Introduction to the IPMDAR Data Deliverable – Tips for Producing the Outputs
Contractors new to earned value management (EVM) often give us a call to help them respond to a government customer request for proposal (RFP) that includes the FAR or DFARS Notice of Earned Value Management System (EVMS) contract clause. Depending on the contract value threshold, the contractor will need to implement an EVMS that can at least produce the contract performance data submittals ($20M or greater) or complete a formal EVMS compliance review ($100M or greater) by a cognizant federal agency (CFA) such as the Defense Contract Management Agency (DCMA). Required data deliverables for a DoD or NASA customer reference the Integrated Program Management and Data Analysis Report (IPMDAR) Data Item Description (DID) as the means to submit monthly performance data. 

What is the objective for placing the IPMDAR on contract?

The government customer wants the monthly source schedule and cost data from the contractor for their own contract performance analysis in a standard format. They need to have reliable schedule and cost data for visibility into current contract performance as well as credible schedule and cost projections for the remaining work. Will the contractor complete the remaining work effort within the contractual schedule and cost targets? The government program manager needs this information for their own planning and budgeting as well as forecasting their funding requirements.

A standard format for collecting the data is important for the government customer so they can perform program portfolio analysis. The DoD established their EVM Central Repository (EVM-CR) to routinely collect contractor data submittals for program portfolio analysis. The data is organized using the MIL-STD-881 (the DoD Standard for Work Breakdown Structures or WBS), as a common basis to organize program data. The IMPDAR DID data submission requirements are defined in the File Format Specifications (FFS) and Data Exchange Instructions (DEI). The FFS and DEI specify the required set of data tables using JSON encoding for the IPMDAR cost and schedule data submissions while narrative text is submitted using Microsoft Word or PDF files so the customer can perform text searches. 

The government program manager can tailor the IPMDAR requirements as defined in the DoD IMPDAR Implementation and Tailoring Guide that complements the DID. For example, they can specify the level of data detail (control account or work package level), whether data can be delivered incrementally, variance analysis options, and requirements for the Performance Narrative Report content.

What is included in the IPMDAR deliverable?

There are three components as outlined below
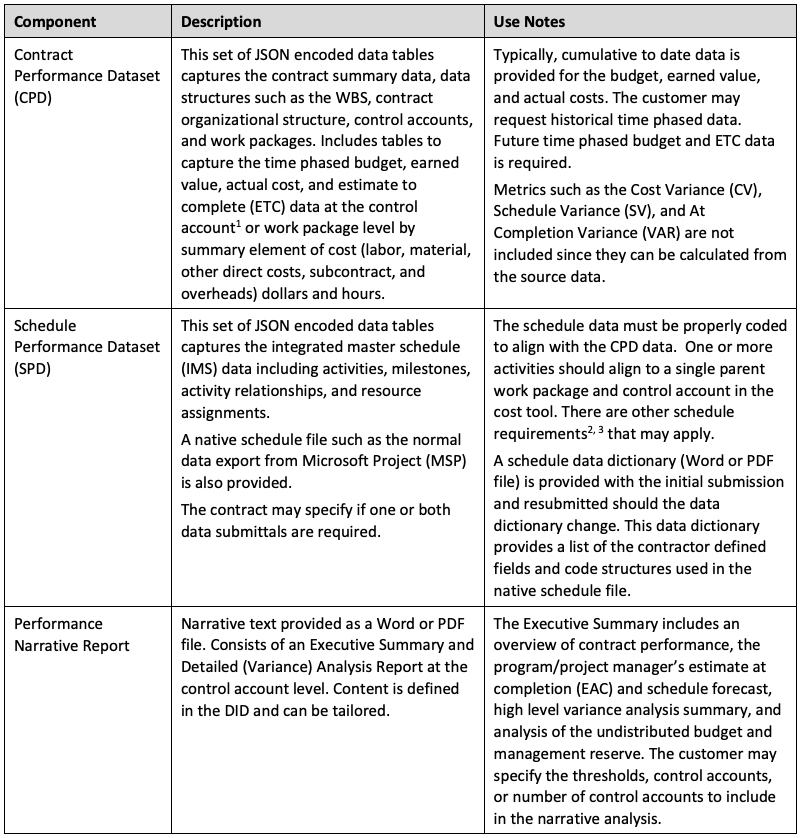
IPMDAR Components

Notes:

  1. At a minimum, the IPMDAR requires data at the control account level with summary element of cost detail. The contract may specify work package level data.
  2. Inputs from a recent schedule risk assessment (SRA) should be included in the native schedule file submission when available. Depending on the schedule tool, the SRA data may need to be a separate file submission (Word or PDF). Results from the SRA along with other schedule analysis discussions (critical path, driving path, and schedule margin) are required to be included in the Detailed Analysis Report narrative. 
  3. The customer may request the results from a schedule data quality assessment and health metrics be included in the Detail Analysis Report narrative. 

What is required to produce the IPMDAR deliverables? 

For contractors new to EVM, one of their first objectives is to figure out what schedule and cost tools they need to be able to provide the required IPMDAR data and narrative analysis to their customer. H&A earned value consultants are sometimes asked to provide recommendations on commercial off the shelf (COTS) tools for this purpose. Much depends on what the contractor already has in place. 

Common schedule COTS tools such as MSP or Oracle Primavera P6 that have already been implemented will require an add-on to produce the SPD. Keep in mind that the IPMDAR does require SRA data and may require results from performing routine schedule data quality assessments. Some COTS add-ons to MSP or P6 are able to produce the typical schedule data quality metrics as well as produce the SPD. Other COTS scheduling tools such as Deltek Open Plan incorporate the SRA functionality, data quality metrics, and the ability to produce the SPD as part of the core product capabilities.

In most instances, contractors new to EVM do have an accounting/financial system in place to at least capture some level of contract or program/project budget and actual cost data. There may also be some capability to produce ETC data required for EAC financial analysis. The issue is organizing the complete set of time phased cost data (budget, earned value, actual cost, ETC) at the control account and work package level by summary element of cost that aligns with the schedule activity data. A contractor may be able to get by with Excel for a small project, however, it is time and cost prohibitive to create Excel macros to produce the CPD. Most COTS EVM cost tools are able to produce the CPD and have successfully completed the DoD EVM-CR data submission validation checks. This is a better alternative to building an in-house tool.

A data analysis tool such as Encore Analytics Empower is also a good option. Empower can import the time phased cost data from Excel or other COTS EVM tools and produce the CPD output. Empower can also import data from common COTS schedule tools. The benefit to using Empower is the ability to analyze the schedule and cost data in one place to verify alignment, produce interactive dashboards and a variety of analysis data views, and produce the IPMDAR Performance Narrative Executive Summary and Detailed Analysis Report.

Top Three Tips for Implementing Tools to Produce the IPMDAR Outputs

Here are a few tips from H&A’s earned value consultants on implementing tools to support the IPMDAR data submittals. Focus on getting the basics right.

  • Continuously verify the quality of the schedule and cost data. Routinely perform schedule data quality assessment and health checks to proactively resolve schedule construction, status, or data issues. Perform routine cost data validation checks such as earned value and no actual costs for a work package or the cumulative to date earned value exceeds the budget at completion (BAC). Correct all data anomalies before producing the deliverables.
  • Continuously verify the schedule and cost data are in alignment. Consistent schedule and cost data coding is critical to ensure integration and traceability. 
  • Anticipate the scope and level of data detail required. This can impact tool configuration, data structures, and data pulled from other business systems such accounting. For example, be prepared to provide the work package level of detail; actual costs will need to be available at this level. Another example is providing schedule risk assessment inputs; this is usually required at intervals specified in the CDRL.

H&A earned value consultants routinely help clients with constructing the schedule to support the IPMDAR data requirements, setting up the process to do routine data quality checks, integrating the schedule and cost data, and verifying the data before producing the performance reporting data submittals. Another common focus is producing clear and concise variance analysis narrative content. 

We can do the same for you. Call us today at (714) 685-1730 to get started.

Introduction to the IPMDAR Data Deliverable – Tips for Producing the Outputs Read Post »
Determining Responsibility for Indirect Cost Variance Analysis – Part 3

, , ,

Indirect Cost Variance Analysis Process

The debate that has continued since the inception of the earned value concepts in the 1960’s has been: “Who should report on and analyze the cost variances attributable to indirect costs?”

This blog is the third in the series of blogs to help answer this question.  The first blog covered a few fundamentals about how indirect cost rates are established to set the stage.  The second blog discussed how indirect rates are applied and how project personnel display indirect costs for internal or performance reporting.  This blog concludes the discussion on the indirect cost variance analysis process.  It covers what the EIA-748 Standard for Earned Value Management Systems (EVMS) and related government agency guides have to say on the subject as well as discussing the best option for determining who is responsible for indirect cost variance analysis.  

Throughout a project’s execution phase, project managers and control account managers (CAMs) conduct their respective performance analysis at varying levels of detail to identify significant cost and schedule variances as well as variances at completion (VAC).  They use variance thresholds to focus on the work elements where challenges or problems are occurring.  As needed, they identify the root cause of the variance and determine the best path forward to mitigate or otherwise reduce the impact of an unfavorable variance.  

This effort includes performing additional analysis not just by the direct elements of cost (labor, material, subcontract, or other direct costs (ODCs)), but also by the indirect costs applied to those direct cost elements to identify the root cause.  For example, the CAMs check for labor variances (rate or efficiency/volume) and material variances (price or usage) to identify any potential issues.  As a side note, remember the rates used to calculate earned value are the same rates used for budget values.  Likewise, actual costs are collected into the same direct cost elements of cost and indirect cost pools as the budget plan elements of cost.  Those actual rates may vary from the budget/earned value rates.

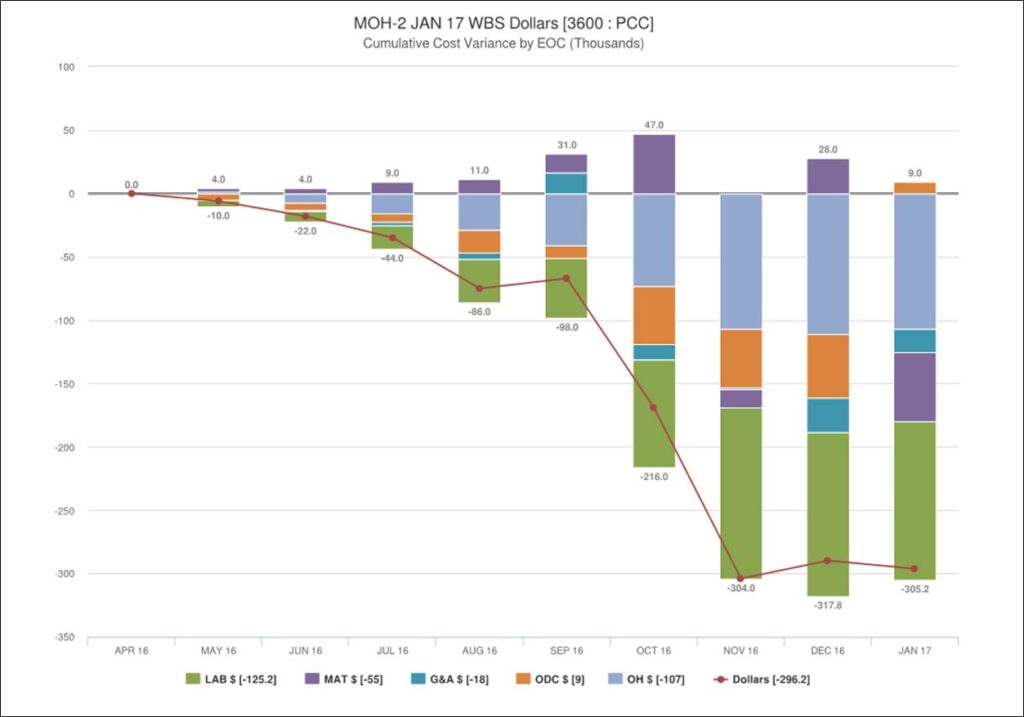
At the total project level, a project manager performs indirect element of cost analysis.  They need to assess whether indirect costs are contributing to the project’s cost variances and quantify the impact.  Since indirect costs are directly related to the base time phased direct costs, it follows the variances for the element of cost categories are similarly skewed.  Figure 1 shows an example (produced from Encore Analytics Empower) of a contract with the variances attributable to the elements of cost (see previous 3-part blog: Planning and Managing EVM by Elements of Cost (EOC)). The indirect cost variances tend to vary with the changes in the direct costs base and/or indirect elements of cost over time at a pool level.  While not common, these could be different from month to month (the lightest blue shaded boxes in Figure 1) when annual, semi-annual, or quarterly rate adjustments occur (the project manager would be notified when these occur).  

Figure 1: Example Cumulative Variance Analysis by Elements of Cost

The project manager and CAMs are also responsible for completing their variance analysis reports.  These include the Integrated Program Management Report (IPMR) Format 5 (Explanation and Problem Analysis) or Integrated Program Management Data and Analysis Report (IPMDAR) Performance Narrative Report.  As part of this analysis, they need to discuss whether rate changes are impacting the project’s current and cumulative cost and schedule variances, as well as the calculated EAC (cumulative to date actual costs plus ETC). 

Customers often require additional indirect cost detail on the formal performance reports when thresholds are exceeded.  The narrative reports are used to address those indirect cost pool base versus rate variances.  Project managers and CAMs (when indirect costs are displayed as part of their budgets), need base versus rate variance analysis from finance or accounting.  Finance or accounting is responsible for establishing the indirect cost rates to date and forecasting what the indirect rates will be for future fiscal years. 

Who is responsible for the indirect cost variance analysis?

Back to our original question: “Who should report on and analyze the cost variances attributable to indirect costs?”  Can the EIA-748 Standard for Earned Value Management Systems (EVMS) 32 guidelines provide any guidance?  There are also various government agencies that place EVMS requirements on contracts.  Do their policies, compliance business practices, or standard operating procedures provide any guidance?  

The fact is, the EIA-748 Guidelines, dating back to the Cost/Schedule Control Systems Criteria (C/SCSC) in the 1960s, have never specified the level where the management and analysis of indirect costs must occur.  The founders of the earned value concept realized there are several levels of management where indirect rates are applied versus the level at which they are displayed for management.  

The EIA-748 Standard for EVMS (Rev D) Guidelines say the following:

4. Identify the organization or function responsible for controlling overhead (indirect costs).

13. Establish overhead budgets for each significant organizational component of the company for expenses, which will become indirect costs. Reflect in the program budgets, at the appropriate level, the amounts in overhead pools that are planned to be allocated to the program as indirect costs.

19. Record all indirect costs which will be allocated to the program consistent with the overhead budgets.

24. Identify budgeted and applied (or actual) indirect costs at the level and frequency needed by management for effective control, along with the reasons for any significant variances.

The Defense Contract Management Agency (DCMA) Cross Reference Checklist (CRC) sub-questions for these guidelines do not specify any particular level where these actions must occur, and do not even mention the control account level.  For example, for the Guideline 4 sub-questions, they reference “the management position” assigned the responsibility and authority for controlling indirect costs.  For one of the Guideline 24 sub-questions, they ask: “Are the variances between budgeted and actual indirect costs identified and analyzed at the level of assigned responsibility for their control (indirect pool, department, etc.)?”  

Likewise, the Department of Energy’s (DOE) detailed Compliance Review Checklist is equally non-specific on the level of management where these actions occur.  Below are excerpts from that DOE document with text highlighted for reference.

E.1E.1 – Indirect Account Organization Structure 
E.1.1Indirect procedures must clearly identify managers who are assigned responsibility and authority for establishing budgets and controlling indirect costs and who have the authority to approve expenditure of resources.
E.1.3The management process for establishing and controlling indirect cost rates should be documented to ensure responsibility is clear.
E.2E.2 – Indirect Budget Management 
E.2.2The contractor must establish indirect (i.e., overhead, burden, cost of money, and G&A expense) budgets at the appropriate organizational level for each pool and cost sub‐ element.
E.2.3Contractor recurring DOE rate performance reviews should be conducted on a regular basis (i.e. monthly, quarterly, etc.) to ensure effective control and management of the indirect expenses and indirect budgets.
E.3E.3 – Record/Allocate Indirect Costs 
E.3.2Periodically, reviews must be made to assure that indirect costs are being charged to the appropriate indirect pools and by the appropriate incurring organization.
E.3.3If incurred indirect costs vary significantly from budgets, periodic adjustments must be made to prevent the need for a significant year‐end adjustment.
E.4E.4 – Indirect Variance Analysis
E.4.1This guideline requires a monthly documented indirect cost analysis to be performed by those assigned responsibility, comparing indirect budgets to indirect actual costs and explaining the cause of resultant variance(s).
E.4.4The contractor should define thresholds for each budget category and a process for management by exception for indirect performance and analysis.

It is not by accident the Guidelines and supporting questions/attributes do not specify any one way all contractors have to manage, analyze, and report on indirect cost variances.  Indirect costs can be handled in a number of different ways.  The Guidelines have always been designed to give contractors the flexibility to manage their projects within the bounds of those Guidelines.  

So, what is a best answer?

While contractors may choose other viable options, a best practice is for the corporate entity responsible for controlling those indirect costs to do the indirect cost variance analysis at the pool levels.  They control the rates, know the reason for variances, and can forecast what the rates will be over time.    As the first blog in this series pointed out, finance or accounting is responsible for establishing and maintaining the direct and indirect rates based on the contractor’s firm and potential direct business base (or volume).  

The designated higher level management entity should also be responsible for providing the necessary indirect cost variance analysis, rate impacts and narrative details to the project managers.  The project managers need to be aware of corporate actions and potential indirect rate revisions that impact the range of EACs they need to prepare for the IPMR or IMPDAR submittals.  This communication is essential so they have the data and narrative text necessary for managing their project, as well as for producing their performance reports explaining the source and impact of indirect cost variances on the project’s EAC to their customer. 

While not a hard requirement, many contractors elect to include both direct and indirect costs in the CAM control account work authorizations.  This does not make the CAMs responsible for these indirect costs since they have little to no control over the indirect rates – they simply apply the current or forecast rates that accounting provides.  But this format does  provide for the necessary visibility CAMs must have regardless in order to conduct the expected variance analysis, inclusive of an assessment of all cost elements (direct and indirect) and price/usage analysis, in order to explain impacts on performance and on their EACs. (See previous blog: EVMS Variance Analysis — EVMS Analysis and Management Reports.) They then forward these to higher level management to incorporate and to provide the rationale for the variances and to determine any corrective action to mitigate the problems. 

Another important advantage of providing CAMs fully burdened budgets, earned value, and actual cost data broken out by the direct and indirect cost elements includes but is not limited to facilitating “make to buy” and “buy to make” decisions because a CAM has an apples-to-apples cost comparison as noted in the second blog. 

Need help sorting out the best levels for reporting and managing your direct and indirect costs?  Call us today at (714) 685-1730.  


Other Posts from this Series

Determining Responsibility for Indirect Cost Variance Analysis – Part 3 Read Post »

Benefits of Earned Value Management

, , ,


This video provides an overview of why Earned Value Management is a benefit to both the company implementing it and their customer.

Video Contents

You can use the links below to jump to a specific part of the video.
0:00 – Introduction
0:12 – EVMS Benefits to Customers
1:01 – EVMS Benefits to Companies
1:54 – Mutual Benefits of Earned Value


More EVMS Training

If you liked this video you can purchase the entire course below. This video is an excerpt from the Department of Defense (DOD) version of this eLearning module. We also offer the same course customized for the Department of Energy’s (DOE) specific Earned Value Management (EVM) implementation/requirements, as well as a version of the course customized for NASA’s EVM implementation/requirements.  

— Purchase This Course —
EVMS DOD Virtual Learning Lab

— Purchase the DOE Version of this Course —
EVMS DOE Virtual Learning Lab

— Purchase the NASA Version of this Course —
EVMS NASA Virtual Learning Lab


EVMS Document Matrix

Not sure what the different requirements are between the DOE and NASA? Can’t remember if Cost and Software Data Reporting (CSDR) is required for an NSA contract? Check out our easy to read Earned Value Management Systems Document Matrix


Earned Value Consulting

Earned value consulting is a process by which a consultant can help a company to better understand the financial implications of their projects. This understanding can then be used to make more informed decisions about whether or not to undertake a project, and also to ensure that the project is completed as efficiently as possible. The goal of earned value consulting is always to improve the bottom line for the company.

Looking to improve your company’s bottom line? Earned value consulting can help! Our experienced consultants can analyze your project costs and help you make informed decisions about whether or not to undertake a project. We’ll also help you stay on track during the project’s execution, ensuring that it stays within budget and on schedule. Contact us today to request a free consultation.


All Online Courses

All Online Courses Available from Humphreys & Associates

Earned Value Training

Other Posts in this Series

Benefits of Earned Value Management Read Post »

Earned Value Training Help is Available

, ,
Earned Value Training Help is Available

Do any (or many) of these situations apply to you?

  • The Project has to comply with the EIA-748 EVMS Standard! What is that? How do we do that?
  • You have a new contract of over $20 Million, and you need to get yourself, your staff, and all the Project personnel up to speed on your new contractual Earned Value requirement.
  • The RFP says the company must have an Earned Value Management (EVM) certification. How can we respond to the RFP?
  • Your contract is over $100 Million and now you must have and demonstrate a Certified Earned Value Management System (EVMS).  How do you do that?
  • How do you get a compliant EVMS Description in the first place?
  • You have an Integrated Baseline Review (IBR) coming up and don’t have a clue about what that entails. 
  • You reviewed company training materials and everything dealing with Earned Value is out of date; and it is going to cost thousands to update the materials and keep them up to date! 
  • What are Control Account Managers (CAMs)? Must we have CAMs to do Earned Value? How do I get CAMs/Train them?
  • I used to have great CAMs, but none of my new CAMs can spell EV.  How do I train them? 

You Are Not Alone

If you answered “yes” to any of these, don’t feel like the Lone Ranger.  Even though the Earned Value concept has been around for over 50 years, the requirement can still be new to your company, new to your contract, and new to your employees.  Most will not have learned EVM in college.  Even companies that have been using EVM for years face a recurring need for training.  We’re pretty consistently seeing a turnover of 20-40% of our experienced CAMs each year across the industry. 

If you answered “yes” to several, I’m sure you’re a bit overwhelmed and asking yourself, how can we possibly meet all these requirements?

Over 40 Years of Experience

Well, don’t despair.  Humphreys & Associates, Inc. (H&A) has just what you need to get you through all those situations, and more.  For over 42 years, H&A has been the leader in providing EVM proposal support, EVMS Requirements/Gap Analysis support, EVMS Design, Implementation support, IBR Preparation, and EVMS Review/certification preparation, staff augmentation, and of course, EVMS and Project Management Training. 

H&A has trained over 950,000 people around the world in all aspects of the Earned Value requirements and has built the largest, most comprehensive library of training materials in the Earned Value Management consulting industry.  We have tailored training materials and have trained and supported contractors whose customers have been from DOD, DOE, NASA, FAA, HHS, as well as international customers such as the Australian DOD, the Canadian DND, Sweden Defense, and the UK.

EVMS Training Library

Our actively maintained library includes:

  • Basic and Advanced Courses in Earned Value Management and
  • Control Account Manager/Project Controls Staff Training and Certification;
  • EVMS Review training to prepare upper management and project teams for:
    • Earned Value Management System Review,
    • Integrated Baseline Review (IBR), and
    • Internal/Joint/External Surveillance;
  • Specialized training in:
    • Developing a WBS,
    • Planning Techniques,
    • Project Scheduling,
    • Baseline Establishment,
    • Materials Management,
    • Subcontract Management,
    • Basic and Advance Variance Analysis,
    • Estimating,
    • Change Management,
    • Government Reporting requirements,
    • OTB/ OTS incorporation, and
    • Agile Software Development

Real-World Application

Our curriculum makes extensive use of real-world examples and case studies to extend the process of learning into application.  We offer these hands-on courses in a variety of settings and formats to meet your needs. 

Public offerings are open to the industry at large and are particularly useful when you have a limited number of individuals needing the training or those individuals who are widely geographically separated. 

In-house offerings at your facilities allows us to meet the training need at one location or for one specific team and can include specifics of your system description.  

Earned Value Webinars

Webinar offerings of the two courses above and our Virtual Learning Lab (VLL) format are available, especially in these times of limited travel.  Webinars of the public and in-house training courses rely on the same content as the in-person courses with the addition of virtual interaction opportunities to increase student involvement and enhance learning.  Our Virtual Learning Lab (VLL) format provides an opportunity for busy individuals to learn at their own pace and time of their choice – even if they are working from home.  The VLL makes extensive use of video presentations and application case studies to enhance the learning environment and ensure the students continue to apply the knowledge they have gained. 

Training Materials

If you have an existing training staff, H&A can even be your source for training materials.  Most of our courses are available for purchase/licensing and our staff of EVMS experts can tailor them to any company environment.  The big benefit here is you leveraging H&A active involvement with EVM requirement changes to keep the material up to date and your training staff don’t have to do it.  In the end you get an up-to-date course without out committing the staff and costs to do the work.  This approach also aligns your material across all our offerings to provide you delivery flexibility with a consistent core content.       

In addition to providing course materials, H&A also can provide Train-The-Trainer sessions in those courses, so your company’s training department can understand and become comfortable with the training materials and updates.

EVMS Certification Programs

Our Certification programs go beyond the public or in-house training courses to create the Qualified CAMs and Project Controls (PC) personnel that are integral parts of a successful EVMS implementation.  These roles are where “the rubber meets the road” for EVMS.  CAMs and PCs will be expected to demonstrate how the company’s EVM System is actually operating on a day-to-day basis.  H&A offers comprehensive and rigorous Certification Courses for both of these important functions so you can be assured that your people not only understand Earned Value concepts but have demonstrated the ability to address the requirements or even problems that can arise on a Project. 

Mock Reviews

To enhance the review training listed above (EVMS, IBR, and Surveillance) and best prepare your organization for these events, H&A also provides teams of our consultants who can conduct Mock Reviews for all three of these events.  These mock reviews simulate each type of government review, including the conduct of CAM and other manager interviews, the running of metrics testing, and the preparation of in-briefs and exit briefs all of which are integral parts of a government EVMS Review.  These Mock reviews can also be used as on-the-job training for company personnel who may be required to conduct IBRs or Surveillance at a subcontractor’s facility. H&A can also augment your company teams in conducting these subcontractor reviews to extend the training while helping your team complete required tasks. 

Agile

H&A has a team of experienced Agile Coaches who are also experts in integrating Agile and Earned Value Management methodologies. H&A also has a vast library of Agile and EVM training materials that can be tailored to meet specific client needs.

Specialized and Experienced Training

Our specialized training courses have been developed over time to address the specific training needs of past clients and provide in-depth, focused training in a variety of topics to enhance your application EVM to effectively manage your projects.  These courses build on the general knowledge provided by the basic courses to make your team more effective and efficient in each topic area.  In cases where your team needs specific, focused training and you don’t find it listed here, we would be happy to discuss the situation and provide a recommended approach to make you successful.      

Each H&A Senior Team Lead typically has over 30 years of experience in Industry, in Government, and/or in consulting – so there is virtually no situation or problem that they have not encountered before. So, although your company may be overwhelmed by the EVMS requirements and the expectations of your customer, you can rely on our H&A team of experts to get you through it all successfully. 

So please, take a look at the H&A website and all that we have to offer, and then give us a call at (714) 685-1730, or email us so we can get you started on the road to EVMS success. We look forward to helping you be successful!

Earned Value Training Help is Available Read Post »

Tips for Implementing Effective Earned Value Training

Banner Image - Tips for Implementing Effective Earned Value Training

Likely you have been on the receiving end of this advice.  The common solution to every problem seems to be: do more training.  Well, yes, that is often a logical conclusion.  The hard part is, how do you implement earned value training that actually helps project personnel improve their knowledge levels and skill sets that makes a difference in how projects are managed?  Conducting training just to check something off a to-do list is a waste of everyone’s time.

Here are a few tips to help you implement an effective EVM training plan.

Tip 1 – What’s the problem you want to resolve?

A clear understanding of the problem you want to solve helps determine the scope of the training, who needs the training, and what kind of training will make a difference.  Here are a few examples to illustrate a range of the scope of the training from the complex to targeted training.

  • The good news?  You just won a government contract with EVMS contract clauses.  The bad news?  Your company’s project control system is immature at best and will need to become more disciplined to support the contractual EVMS requirements.  You are going to need a robust education and training plan to rapidly increase the project control maturity level of your company.  Likely you will need to enhance your current project control practices, add process and procedures, perhaps implement new software tools, and educate a variety of functional managers and project personnel on the upgraded best practices they will need to follow. 
  • You have an influx of new project personnel that need to learn the ropes.  Where are they with their current skill sets and what will help them improve?  Perhaps they have a basic understanding of project control or scheduling, but don’t know how to apply your company’s preferred practices or how to effectively use the software tools.  They may need a broader earned value training plan that covers a number of disciplines or hands-on workshops that combine process training and using the software tools to effectively perform their project control tasks.
  • You have a contractual or audit event coming up.  Examples include an Integrated Baseline Review (IBR) for a new project or the DCMA is coming in to do a compliance review.  That means you need to make sure all levels of project personnel are prepared for the review and that quality schedule and cost data have been established.  Different types of focused training or mentoring is often required to prepare for these events where there is interaction with the customer project manager or audit agency personnel.  Personnel knowledge, the EVMS, how they apply the EVMS on their project, and data traceability will all be assessed.   
  • As part of your internal process improvement activities, you discover a number of control account managers (CAMs) are having difficulty producing useful variance analysis report (VAR) narratives.  Or, perhaps the schedulers are having trouble creating or maintaining their integrated master schedules (IMS) to the level of data quality you expect. Targeted or role specific training could make a difference here.

Tip 2 – Determine what you need to accomplish your training objective

Here is a sort list of factors to consider as you begin to sort out what type of training or training materials you need to have in place to accomplish your training objectives.

  • Do you intend to create and maintain a set of EVM related training materials internally?  What types of materials you intend to maintain?  This could be a range of materials such as instructor led presentation and course materials, role specific training materials or templates, desktop instructions, online help, or self-paced instructional videos.  Do you have the personnel, time, and budget to do this?  Do you have the internal EVM expertise?  You may need help creating your internal materials or you may need to rely on outside services to supplement your internal training. 
  • How do you intend to deliver the earned value training, how often, and how many people?  A day or two dedicated to classroom instruction may or may not be option.  Perhaps project personnel need to complete the training remotely or are only available for a short duration.  How do you accomplish your training objectives and verify personnel are applying what they are learning? 
  • You need to prepare a contractual event such as an IBR.  This presents a different set of factors and you may or may not have a process or EVM expertise in place to handle this.  Depending on your company, you may have the internal project management resources you can pull from another division to help the project personnel prepare for the event and perform an independent review of the schedule and cost data.  How do you intend to handle these events?
  • Targeted training to address a recurring issue or a unique project situation such an implementing an over target baseline/over target schedule (OTB/OTS).  For example, targeted training would be useful for CAMs or schedulers that need help getting to the next level of proficiency.  One option could be to solicit the help of an internal “power user” to help mentor project personnel in how to do things or how to effectively use the software tools.  Or, you could leverage the expertise of outside services to help mentor them and expand the base of proficient project personnel over time.

Tip 3 – Who you select to help you with your earned value training objectives matters

There are a number of companies that offer earned value and related training.  There are a number of factors to consider as you start to evaluate their services, expertise, scope and availability of training materials, and range of training options. 

There is a reason why H&A has been the leading provider of earned value training and earned value consulting services for over four decades.  We have proven, cost effective approaches to increasing your project control team’s skills so they become more valuable assets to your organization.  For example:

  • We have built the largest, most comprehensive library of training materials in the EVM consulting industry including basic and advanced courses as well as specific topic areas such as developing a WBS, OTB/OTS, preparing a VAR or government performance report, subcontract management, change management, or IBRs. 

What’s the benefit to you?  Should you need source material for a training course, our courses are available for lease and can be tailored to your environment.  You don’t have to start from scratch.  We actively maintain our course materials and provide updates as requirements change over time including specific versions for DoD, DOE, and NASA.  This takes the burden off you and reduces the cost of keeping up with changes.  We provide train-the-trainer sessions for the courses, so your company’s training department can become proficient with the materials to build out your internal training library over time. 

  • We offer our hands-on courses as public workshops, in-house, or remotely.  We also offer our most popular three-day workshops as distance learning courses.  We refer to these as our EVMS Virtual Learning Lab and Scheduling Virtual Learning Lab (VLL) so your project personnel can learn at their own pace – even if they are working from home.  The benefit is you can select a combination of training options to fit your needs as well as personnel availability or location.
  • We offer two career path certifications you could leverage to assist project personnel looking to advance their knowledge and skills.  We created the H&A Control Account Manager (CAM) Certification program over 5 years ago and approximately 600 people have gone through this rigorous certification process.  We also created a Project Control/Analyst (PC/A) Certification for personnel that support CAMs and Project Managers.  These certifications mean the individual has demonstrated a knowledge level that establishes a sound foundation for success as a CAM or PC/A.
  • H&A senior personnel typically have over 30 years of experience in industry, government, and consulting across a variety of industries.  When you need help with an IBR or government compliance review, our consultants can help prepare and mentor your project personnel to successfully navigate the review process as well as perform data traces with them to verify the quality of the schedule and cost data.  When you need help training personnel on a specific EVM topic such as OTB/OTS or how to prepare a VAR that requires additional EVM expertise, we can conduct the training for you whether in-house or remotely.  

You can rely on the H&A team of experts to help you with your EVM, scheduling, and related training needs.  For more information about our courses, descriptions, and delivery options, visit our web page at: https://www.humphreys-assoc.com/evms/evms_training_courses.php. 

Tips for Implementing Effective Earned Value Training Read Post »

Earned Value Consulting – Common Problems Found in EVMS and Recommended Corrective Actions

, , , , , , ,

Humphreys & Associates (H&A) has the opportunity to work with many kinds of clients who operate EVM Systems for all kinds of customers. We are regularly called on to help them our clients review and improve their EVMS.

H&A has identified several recurring EVMS issues and also the most common ways to prevent or correct these issues.

Earned Value Consulting – Common Problems Found in EVMS and Recommended Corrective Actions Read Post »

Scroll to Top