A common Earned Value Management System (EVMS) compliance and surveillance review finding are issues with a contractor’s estimate at completion (EAC) process. A credible EAC is essential to successfully manage all contracts and projects.
EACs are important because they provide a projection of the cost at contract or project completion, which is also an estimate of total funds required by the customer. It matters because EACs represent real money. When the most likely EAC exceeds the negotiated contract cost, the contractor’s profit margins may be at risk. It also creates a problem for the customer when the most likely EAC exceeds their funding limits.
We recently updated our blog titled Maintaining a Credible Estimate at Completion (EAC) to highlight why this is a good time to review and potentially update your estimate to complete (ETC) and EAC processes. The updated blog added content specific to:
Incorporating integrated master schedule (IMS) analysis to test the realism of the EAC to identify any disconnects with the cost-based independent EACs (IEACs). It is equally important to determine a realistic forecast completion date (FCD).
Ensuring control account managers (CAMs) are in a position to substantiate their schedule timeline, resource requirements, and cost estimate to complete the remaining work. It is equally important that project managers proactively take the action of “scrubbing” the CAM’s detail ETC/EAC and verifying the data to gain a better understanding of the project’s current state. This improves the quality of the project-level forecast completion date as well as the range of project-level EACs.
Suggested actions to review and enhance current processes from basic steps, such as incorporating an analysis of the IMS Current Execution Index (CEI) to gain an understanding of how well project personnel can forecast into the future, and taking advantage of AI tools to provide additional data analysis insight.
In addition, the publication of the EIA-748-E Standard for EVMS revised 27 guidelines and related updates to government agency guidance such as the DoD EVMS Interpretation Guide (EVMSIG) will require contractors to review and remap EVM System Description content to the revised set of guidelines. The updated blog emphasizes this is a good time to revisit internal ETC/EAC processes and procedures to determine where improvements can be made as well as to ensure project personnel are following the documented processes. The EIA-748-E split the EIA-748-D Guideline 27 into two guidelines. The EIA-748-E Guideline 20 is specific to the control account level EACs and Guideline 23 is specific to the project level EACs. An EVM System Description should have content specific to the process at the control account level as well as the project level that can easily be mapped to the EIA-748-E Guidelines 20 and 23.
Do Your Internal Processes and Procedures Need a Refresh?
H&A earned value consultants routinely assist contractors with updating their internal processes and procedures to reflect the evolving EVMS requirements and guides, regulatory environment, and toolset capabilities. Workflow steps can often be simplified and the quality of performance analysis can be improved with a refreshed approach that reduces the time needed to produce reliable and actionable information. Call us today at (714) 685-1730 to get started.
A common client request is to assist them with sorting through the various DoD contractual reporting requirements and contract value reporting thresholds that apply. We frequently run into situations where a contractor needs clarification on why they have a Cost and Software Data Reporting (CSDR) requirement and whether they should seek to waive the requirement. Subcontractors to a prime often question the requirement to provide actual cost data directly to the DoD, especially for Firm Fixed Price (FFP) contracts.
Background
CSDRs are the primary means the DoD uses to collect data on the development, production, and sustainment costs incurred by contractors performing DoD acquisition contracts. It is a DoD system for collecting actual costs, software data, and related business data. The resulting data repository serves as the primary source for contract cost and software data for most DoD resource analysis efforts including cost database development, applied cost estimating, cost research, program reviews, analysis of alternatives (AoAs), and life cycle cost estimates.
CSDR reporting requirements are determined by the contract value regardless of the acquisition phase and contract type. In general, CSDR reporting is required for Acquisition Category I-II programs and Information System (IS) programs valued at more than $50M. They can also be required for Middle Tier Acquisition programs (greater than $20M) and other programs (greater than $100M). Risk can also be a determining factor regardless of the contract value.
DoD Instruction (DoDI) 5000.73, Cost Analysis Guidance and Procedures (March 2020), provides additional details about the cost data reporting. Table 1 in the 5000.73 lists the cost reporting requirements contract value thresholds. The DoD Manual 5000.04 Cost and Software Data Reporting (May 2021) is the primary requirements document for the development, implementation, and operation of the DoD CSDR system to ensure data reported is accurate and consistent.
About CADE
The Office of the Secretary of Defense Cost Assessment and Program Evaluation (OSD CAPE) established the Cost Assessment Data Enterprise (CADE), a secure web-based information system that hosts the controlled unclassified CSDR repository, the Defense Acquisition Cost Information Management System, and the forward pricing rate library. CADE also contains a selected acquisition report database, a contracts database, data analytics capabilities, and a library containing cost estimating content such as cost analysis requirement descriptions and cost estimates. CADE is access-controlled, and available through the public-facing CADE Portal website.
Similar to the cost estimating and proposal pricing functions within contractor’s organizations that rely on historical actual costs to assess the validity of a proposed cost estimate, independent and sound cost estimates are vital for effective DoD acquisition decision making and oversight. CADE plays a critical role in capturing the expenditure, technical, and programmatic data after contract execution in a consistent manner to enable independent cost estimating and analysis. This cost estimate data is essential to support efficient and effective resource allocation decisions throughout the planning, programming, budgeting, and execution process for the DoD.
CSDR Reporting Requirements
There are a series of Data Item Descriptions (DIDs) for this reporting requirement. Some forms are submitted electronically using DoD defined XML schemas, Excel, or JSON encoded data in accordance with a File Format Specification (FFS) and Data Exchange Instruction (DEI). The list of DIDs are as follows. These DIDs can be downloaded from the CADE website.
Contract Work Breakdown Structure, DI-MGMT-81334D (May 2011).
Cost Data Summary Report, DI-FNCL-81565C (May 2011), DD Form 1921, XML Schema.
Functional Cost-Hour Report, DI-FNCL-81566C (September 2015), DD Form 1921-1, XML Schema.
Progress Curve Report, DI-FNCL-81567C (May 2011), DD Form 1921-2, XML Schema.
Sustainment Functional Cost-Hour Report, DI-FNCL-81992 (May 2011), DD Form 1921-5, XML Schema.
Contractor Business Data Report, DI-FNCL-81765C (March 2021), DD Form 1921-3, Excel.
Software Development Report, DI–MGMT-82035A (October 2022), DD Form 3026-1, XML Schema.
Software Maintenance Report, DI–MGMT-82035A (October 2022), DD Form 3026-2, XML Schema.
Enterprise Resource Planning (ERP) Software Development Report, DI-MGMT-82035A (October 2022), DD Form 3026-3, XML Schema.
Cost and Hour Report (FlexFile), DI-FNCL-82162 (November 2017), JSON encoded data file following FFS and DEI.
Quantity Data Report, DI-MGMT-82164 (November 2017), JSON encoded data file following FFS and DEI.
Maintenance and Repair Parts Data Report, DI-MGMT-82163 (November 2017), Excel.
Technical Data Report, DI-MGMT-82165 (November 2017), Excel.
The Cost and Hour Report (FlexFile) and Quantity Data Report play a critical role in collecting cost data from contractors for the DoD data repository because they use JSON data encoding to organize the content. They are intended to replace the legacy 1921 series of paper-based formats including the DD 1921, 1921-1, 1921-2, and 1921-5. It also requires contractors to provide significantly more historical cost data than the 1921 formats. As a result, the DoD cost estimating community has additional insight into historical costs. The goal is to establish a common framework and standard nomenclature to collect data from different contractors, all of them with unique cost accounting structures, that are mapped to the DID, FFS, and DEI requirements for use in the data repository.
Establishing a Consistent, Repeatable Process to Produce the CSDR Data Deliverables
For contractors new to the CSDR reporting requirements and in particular, the FlexFile JSON data encoding, can appear to be daunting. That’s where software tools such as those from Midnite Dynamics can help. Midnite Dynamics specializes in assisting contractors with producing the CSDR data deliverables.
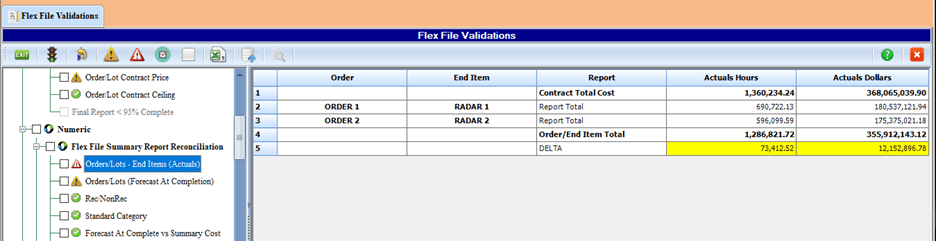
Their software tool, C*CERT+, streamlines, automates, validates, and produces the legacy 1921 family of Excel and XML reports as well as the FlexFile and Quantity Data Report JSON submittals. C*CERT+ eliminates what otherwise is a manually intensive, resource draining, tedious and costly effort subject to recurring rejections. It is one thing to create the required legacy reports or FlexFile JSON files for submittal, it is another to pass the submittal validation process. C*CERT+ provides numerous data validations and analysis reports to ensure the data is 100% compliant before it is submitted. For example, the software includes over 90 FlexFile validations to ensure data compliance as illustrated in Figure 1.
Figure 1: Example of FlexFile data validation results.
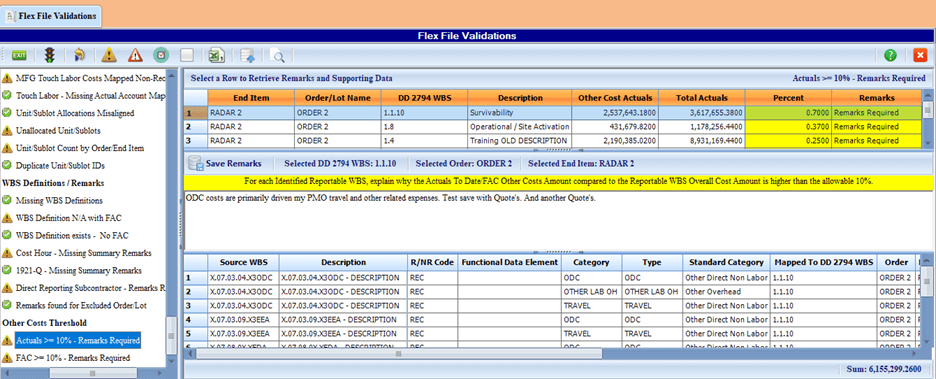
The software includes a Validation and Remarks utility to analyze the source data details that could result in a Validation Trip. Remarks can be entered directly into the validation module for anything that requires an explanation. This is illustrated in Figure 2. This narrative is included with the data submittal.
Figure 2: Example of providing remarks about the FlexFile data content.
C*CERT+ also interfaces with existing EVM cost tools and accounting systems to produce the existing legacy 1921 reports, the FlexFile, and other data submittals as well as to consolidate separate projects/CLINs/task orders into a single contract report.
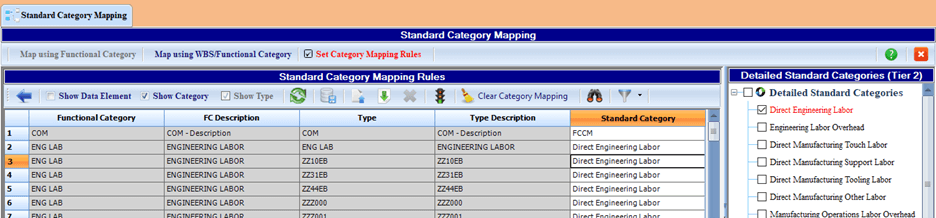
Once the C*CERT+ Standard Category Mapping Rules are set up, they can be shared throughout the corporation or business unit to establish a standard and repeatable process for producing the data deliverables. This mapping process translates the contractor’s source data into an output that matches the CSDR data submittal format rules. This saves a tremendous amount of time and makes it much easier to consistently produce the CSDR data deliverables. An example of the Mapping Rules is illustrated in Figure 3.
Figure 3: Mapping Rules translate contractor unique cost data into a format that matches the CSDR data submittal requirements.
Do your process and procedures or training materials need an update to include specific guidance for project control teams to produce required DoD contractual reports or data submittals using your tool sets of choice? Give us a call today at (714) 685-1730 to get started.
In the complex landscape of project management, ensuring compliance with the EIA-748 Standard for Earned Value Management Systems (EVMS) Guidelines is a critical step for companies seeking to secure and successfully manage government contracts. Humphreys & Associates are leaders in earned value consulting, providing comprehensive strategies and solutions tailored to meet the rigorous requirements of the EVMS approval or certification process by a Cognizant Federal Agency (CFA). This article is the first part of a three-part series aimed at guiding organizations through the process of implementing a compliant EVMS and successfully completing a CFA EVMS compliance review.
Understanding the EVMS Approval or Certification Process
Achieving EVMS approval or certification by a CFA such as the Defense Contract Management Agency (DCMA) or the Department of Energy (DOE) is a structured process that requires careful planning and execution. The process begins with a thorough understanding of the EIA-748 Standard for EVMS Guidelines, which is the foundation for determining whether an EVMS is compliant. The EIA-748 Guidelines define the requirements to establish and maintain an effective EVMS. The approval or certification process involves several key steps, beginning with the initial application and concluding with the CFA formal determination a contractor’s EVMS complies with the Guidelines. Throughout this journey, organizations must demonstrate a thorough understanding of the Guideline requirements and how they are implemented within their project management framework as documented in their EVM System Description.
Steps to Achieve EVMS Certification
Preparation and Self-Assessment: Conducting an internal review of the current project management processes and comparing them against the EIA-748 Standard for EVMS Guideline requirements is an important first step to identify gaps in the system that will need to be addressed.
Training and Education: It is crucial for the team responsible for EVMS implementation to receive proper training to understand the Guideline requirements and how to apply them.
System Description Development: A comprehensive EVM System Description that explains how the organization’s processes meet the EIA-748 Guideline requirements must be developed.
Implementation: The EVMS must be implemented on a project, demonstrating the project team’s ability to use the EVMS and EVM data to manage the project, as well as the system’s functionality in a real-world scenario.
Mock Compliance Review: An internal review, often with the help of an independent third party, should be conducted to verify the EVMS complies with the Guideline requirements as well as to verify the quality of the project’s schedule and cost data to provide timely and actionable information for managing the project.
Formal Compliance Review: A CFA conducts a formal review of the EVMS. This includes reviewing the EVM System Description, performing a detailed examination of project schedule and cost data, conducting interviews with project personnel, and assessing how the EVMS has been implemented.
Importance of Complying with the EIA-748 Guidelines
Meeting the EIA-748 Guideline requirements is not just about compliance; it is about integrating a system that enhances the project management capabilities of an organization. A well-implemented EVMS facilitates better project control, provides early warning signs of performance issues, and supports informed decision-making. Compliance with the Guidelines is often a prerequisite for bidding on government contracts, making a formal EVMS approval or certification a strategic necessity for companies in the defense, aerospace, and construction industries, among others.
Key Requirements for an EIA-748 Compliant EVMS
The EIA-748 Standard for EVMS provides the basic guideline requirements for organizations to establish and implement a system that integrates project work scope with the schedule and cost components to enhance project planning and control. The Guidelines are organized into these process areas:
Organization: The organization guidelines focus on establishing the framework for decomposing a project’s scope of work to level where it is possible to identify management responsibility for the work scope, schedule, and cost components.
Planning, Scheduling, and Budgeting: The organization guidelines are the framework for the planning, scheduling, and budgeting process required to establish the performance measurement baseline, a common point of reference for measuring completed work and communicating the project’s current status.
Accounting Considerations: These guidelines focus on the recurring processes for determining progress and collecting the actual costs for work performed. The objective is to ensure alignment between the budget plan, performance claimed (earned value), and actual costs to continually assess and analyze project performance for potential corrective action.
Analysis and Management Reports: These guidelines facilitate the analysis and use of the performance data to proactively manage the project. An EVMS generates variance data that helps management to focus on areas that are not performing to plan for potential corrective action.
Revisions and Data Maintenance: The integrity of the performance measurement baseline must be maintained to manage the remaining work on a project. These guidelines focus on establishing a controlled process to document, authorize, track, and manage revisions to a project’s scope, schedule, and budget.
Frequency and Importance of Surveillance Reviews
Surveillance reviews are an important part of maintaining a compliant EVMS. Once the CFA has approved or certified a contractor’s EVMS, the contractor is responsible for implementing an annual self-surveillance or self-governance process to ensure the EVMS continues to be implemented on projects in an effective and consistent manner in compliance with the EIA-748 Guidelines. It also ensures the contractor’s EVMS process and procedures, training, and tools are actively maintained over time. The government customer also conducts surveillance for the life a contract, typically on an annual basis. This is a recurring evaluation of the contractor’s management control practices and samples of internal and external reported data. The focus is typically on major system activities, problem identification, and tracking any corrective actions to closure.
The successful implementation of an EVMS that complies with the EIA-748 Guideline requirements is a testament to an organization’s commitment to project excellence. It demonstrates a capability many government agencies require, making it an essential investment for businesses looking to expand their opportunities within this sector. The subsequent articles in this series will delve into the specifics of the EVMS implementation process and the intricacies of preparing for EVMS compliance and surveillance reviews.
This article has provided an overview of the EVMS approval or certification process by a CFA and the importance of complying with EIA-748 Standard for EVMS Guidelines.
Facing an Earned Value Management System (EVMS) compliance review can be an imposing prospect for any organization with EVMS contractual requirements. With strategic preparation and expert guidance from Humphreys & Associates, renowned for their leadership in earned value consulting, this necessity can be transformed into an opportunity for process improvement to ensure an effective and efficient EVMS can be implemented on any project. This comprehensive guide, the first in a three-part series, takes a closer look at the strategic approach necessary for preparing for a Cognizant Federal Agency (CFA) EVMS compliance review. CFAs include the Defense Contract Management Agency (DCMA) for DoD and NASA contracts and the Department of Energy (DOE). A CFA conducts a formal review to determine whether the contractor’s EVMS is compliant with the EIA-748 Standard for EVMS Guidelines. A formally approved or certified EVMS is an EVMS the CFA has determined to be compliant with the EIA-748 Guidelines.
Key Elements in Preparing for an EVMS Compliance Review
A successful EVMS compliance review is predicated on several fundamental elements. Being well-prepared in these areas can make the difference between a review that goes smoothly and one that uncovers issues that require corrective action.
Thorough Documentation: Proper documentation is the backbone of any review process. It’s essential to maintain an EVM System Description that explains how the system complies with the EIA-748 Guideline requirements as well as any agency specific EVMS requirements. This includes documented policies and procedures as well as process flowcharts illustrating system inputs and outputs with responsibility assignments.
Mock Reviews: Conducting internal mock reviews can serve as a rehearsal for the actual review. These practice runs help to uncover any weaknesses in the system and provide a chance to correct them beforehand. Mock reviews also help familiarize the team with the compliance review process, reducing anxiety and ensuring that everyone knows what to expect.
Continuous Training: Regular and comprehensive training ensures that project personnel are familiar with the EVMS processes, know how to use the EVM data, and understand the importance of their role in maintaining quality schedule and cost data. This training should be updated regularly to reflect any changes in EVMS requirements, software tools, or company procedures.
Data Integrity: The accuracy and completeness of project data are crucial. Regular validation checks should be conducted to ensure data in the EVMS are valid, reliable, and traceable. This includes verifying the project data aligns with the corporate financial records and that the system accurately reflects the project’s current status.
Stakeholder Engagement: Effective reviews require the cooperation and understanding of all stakeholders. Engaging them early in the review process helps ensure everyone is on the same page and that the roles and responsibilities are clearly defined. This engagement includes regular communication and involvement in the compliance review preparation process.
Assistance in the Review Preparation Process
Humphreys & Associates provides comprehensive services designed to support organizations throughout the compliance review preparation process. This includes:
Compliance Review Readiness Assessments: These assessments are crucial in determining the readiness of an organization’s system, personnel, and data quality for a compliance review. The assessment identifies areas of strength and those requiring improvement, enabling targeted action to enhance readiness.
Preparation Workshops: Workshops conducted by experienced consultants can train and prepare the team for the compliance. These sessions cover everything from the basics of EVM to the nuances of the review process, tailored to the specific needs of the organization.
Documentation Review: Prior to an compliance review, it’s beneficial to have an external review of the documentation that will be presented. This review can identify areas where additional information is needed and ensure that the documentation accurately reflects the EVMS and compliance with the EIA-748 Guidelines.
Support Services: During the review, having expert support available can alleviate the challenges that may arise. This includes on-the-spot advice and assistance in addressing the CFA’s questions and concerns. Should the CFA issue formal corrective action requests (CARs), Humphreys & Associates can assist with producing and implementing the corrective action plans (CAPs) to resolve the deficiencies as quickly as possible.
Common EVMS Review Findings and Remediation
There are several common findings that an EVMS compliance review might reveal that could potentially impact an organization’s ability to obtain a formal CFA EVMS compliance approval or certification. Being aware of these potential findings and understanding how to address them is key to success.
Inadequate Baseline Control: Maintaining a current and accurate performance measurement baseline is essential. When a government review team finds baseline control to be lacking, it’s often due to inadequate processes for incorporating changes into the baseline or failing to maintain traceability of the changes.
Insufficient Documentation: Documentation gaps can lead to findings of non-compliance. Government review teams need to see evidence that a complete set of processes are in place and that these processes are being followed. This includes having proper version control and evidence of management approvals.
Data Discrepancies: Differences between what’s reported in the project reports and the actual project data can indicate serious issues with data management systems. Ensuring that the EVMS software is properly configured, data validation checks are routinely performed, and that schedule and cost data align can prevent such discrepancies.
To address and prevent these common issues, Humphreys & Associates recommends a proactive stance, with robust change control processes, continuous enhancement of documented practices, and improvements to data management systems to ensure accuracy and traceability.
Preparing for an EVMS compliance review is a critical task that can significantly impact the management and success of government contracts. With the strategies provided here and the support of Humphreys & Associates, organizations can confidently navigate the EVMS compliance review process.
Originally published March 2023 | Revised May 13, 2026
Quick Summary
EVMS compliance and surveillance reviews continue to identify issues related to poor-quality estimates at completion (EAC), underscoring the need for credible EACs to support effective project management, financial integrity, customer confidence, and funding decisions.
Credible EACs require actively maintained, data-driven estimates to complete (ETCs) that integrate schedule, resource, cost, and risk information along with regular management realism assessments and open communications with all stakeholders.
Organizations can improve EAC credibility by avoiding management imposed targets, keeping schedule and cost systems aligned, routinely reviewing the quality of the ETC data, leveraging evolving tools and analytics, and updating processes to align with the revised EIA-748-E guidelines.
The Defense Contract Management Agency (DCMA) as well as other government entities responsible for Earned Value Management System (EVMS) compliance and surveillance continue to identify issues with the quality of contractor estimates at completion (EAC). Using DCMA statistics, EIA-748-D Guideline 27, Maintain Estimates at Completion, is one of three guidelines1 that represent a third of all EVMS Corrective Action Requests (CARs).
Why Credible EACs Matter
A credible EAC is essential to all stakeholders and a foundation for managing projects successfully. Executive management and project managers must have a complete and accurate understanding of the projected contract or project EAC to ensure financial data is not misrepresented (Sarbanes-Oxley). The customer must have confidence in a contractor’s forecast completion date (FCD) and EAC data to understand whether the remaining work can be completed within the contractual period of performance and target cost, or, if not, how long it will take and how much it will cost.
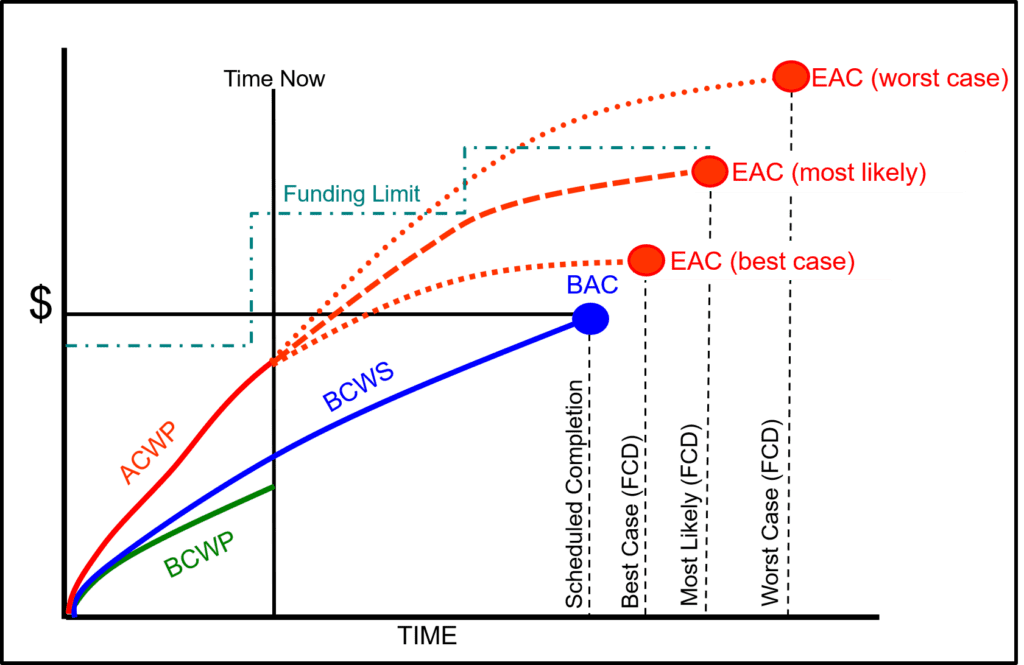
When the most likely EAC exceeds the negotiated contract cost, the contractor’s profit margins may be at risk. Should the most likely EAC exceed the customer’s funding limit, they will need to secure additional funding, modify the work scope, or slow the pace of the project. No one likes schedule or cost surprises.
What determines whether an EAC is credible?
A credible EAC reflects the cumulative to date actual costs of work performed (ACWP) (costs the contractor has already incurred) plus the current ETC. The ETC must provide a realistic estimate of the time and resources required to complete the remaining authorized work using projected rates. It represents the time phased estimate of spending which translates to the future funds required.
EACs should be based on actual costs and performance to date, the nature and amount of remaining scope, assumptions about and projections of future performance for that scope, risks and opportunities, economic escalation, expected direct and indirect rates, subcontract, and material commitments. As illustrated in Figure 1, project managers should routinely evaluate their project’s ACWP, ETC, and range of EACs along with the funding profile to verify amounts expended and forecasted are within the parameters of available contract funds.
Figure 1: Range of Project EACs with Funding Profile
What project control practices help to ensure EACs are realistic?
Three recommended best practices include:
Actively maintaining the detail ETC data every reporting cycle. This starts with updating the current schedule to include all authorized remaining scope along with the resource loaded activities to reflect performance to date and the latest planning (timing and resource requirements) for work in progress and future work effort. This is the basis for updating the time phased cost estimate for in progress work packages that is added to the cumulative to date actual costs as well as the cost estimate for future work/planning packages. Subcontract forecasted schedules and cost must be included. The current schedule forecast dates and time phased cost estimate must be aligned. Actively maintaining the detail data ensures the current schedule and ETC data reflect the project’s current state. The control account managers (CAMs) can substantiate their ETC with relevant data for analysis and take action to address a significant variance at completion (VAC).
Actively monitoring project FCDs and EACs. Project managers that routinely maintain a range of data driven FCDs and EACs (best case, most likely, and worst case) are better prepared to verify the control account FCDs and EACs are realistic, realized risks have been handled, and emerging risks have been identified, assessed, and addressed. Experienced practitioners use various metrics such as comparing the Cost Performance Index (CPI) to the To Complete Performance Index (TCPI) to test the realism of the EAC. They also include a realism check of the baseline and current integrated master schedule (IMS) to identify any potential disconnects with the cost-based indices discussed in a previous blog, Incorporating IMS Information Directly into IEAC Formulas. Managers should scrub the detail ETCs to assess the quality of the estimates and verify the content of the backup data. A good understanding of the detail ETCs is necessary to produce credible project level EACs with crisp rationale and narratives provided to executive management and the customer.
Maintaining open communications with all levels of management, subcontractors, and the customer. The project manager is the main conduit to manage impacts to their project’s FCD and EAC such as when finance changes direct or indirect rates, there are changes in resource availability or a spike in material prices, or the customer modifies the work scope or funding. As a result, project personnel can quickly handle issues or project changes. Direct and open communications with executive management ensures there is a clear understanding of their project’s FCD and EAC.
What are some things to avoid?
H&A consultants often observe practices that negate the value of maintaining the ETC/EAC and can result in an EVMS corrective action request (CAR). The root cause often points to ad-hoc processes or corporate culture. Examples:
Management provides a target FCD and EAC number the CAMs must match. The ETC/EAC should be “the voice of the CAM”. The CAM is saying “if you give me these resources as scheduled, I can finish the job this way.” Any approach that does not respect the voice of the CAM can cause the ETC/EAC to be unrealistic or at least unsubstantiated. Giving the CAM “the date and number” increases the likelihood the FCD and ETC are unrealistic. There may be a valid reason for this directive as a management what-if exercise or to gain a deeper understanding of the situation. When done as a routine management strategy, it diminishes the value of the ETC data to manage the project’s remaining work and prevent cost overruns. The CAMs should be in a position where they can substantiate their schedule timeline, resource requirements, and cost estimate to complete the remaining work. Project managers should be in a position where they can verify the detail ETC/EAC data to establish a level of confidence in their project level EACs they provide to executive management and the customer.
Project personnel take the path of least resistance. This is often an indication of a lack of direction or an established process. They either do not create the ETC data or maintain it on a routine basis. In some instances, the CAMs manage their ETC data to avoid oversight. An old but valid saying is “the tall grass gets mowed” – the CAM purposely doesn’t raise their ETC to a value that would attract attention. Another troublesome approach is to set a cost management tool option to a static EAC; the CAM may manually update the EAC number quarterly at best. The result? The FCD and ETC data isn’t current; there is zero insight into potential emerging issues. DCMA or the customer can easily identify this when they analyze the time-phased ETC data in the Integrated Program Management Data and Analysis Report (IPMDAR) Contract Performance Dataset (CPD) submittal.
Schedule and cost are created/maintained separately. This often occurs when the schedule and cost tools are not kept in sync for the project’s duration. Significant effort may go into ensuring the data are in alignment to establish the performance measurement baseline (PMB). The IMS resource loaded activities are used as the basis for the time phased budget baseline in the cost tool. However, the ETC data in the current schedule may not exist or be actively maintained. Project personnel only maintain the ETC data in the cost tool and fail to verify it aligns with the current schedule activity forecast dates and resource requirements. It is not part of their routine status and analysis process every month.
Taking Action to Review and Enhance Current Processes
A simple step to start with is to use the IMS Current Execution Index (CEI). This is a useful measure of how well a team can forecast just a single month into the future. If a team cannot achieve a high accomplishment rate against just a one-month forecast, any longer-term ETC is questionable. Start simple and focus on improving the one-month accuracy then move on to longer periods. Build confidence in the team’s ability to see and manage the future.
Another basic step. Build time into the process for managers to scrub ETCs. Maybe it is not possible to scrub every control account ETC every reporting period, but a rotational approach where ETCs are scrubbed as often as possible will improve the ETC and improve the understanding of the ETCs.
Innovate. AI tools are rapidly becoming capable of assuming skilled roles such as project analysts and can yield valuable insight. Tools are already available that can evaluate variances and variance analysis reports (VARs). Poor quality analysis translates to poor quality ETCs. Take action that supports improved analysis.
At a higher level, with the publication of the EIA-748-E Standard for EVMS revised 27 guidelines along with the evolving regulatory environment discussed in a previous blog, Revitalizing Earned Value Management Systems, this is a perfect time to review current EVMS ETC/EAC processes. The EIA-748-E split the EIA-748-D Guideline 27 into two parts: EIA -748-E Guideline 20 focuses on the control account level EACs and Guideline 23 focuses on the project level EACs. The DoD EVMS Interpretation Guide (EVMSIG) for Revision E has been updated accordingly.
We recommend reviewing approved EVM System Descriptions to ensure existing content supports the EIA-748-E Guideline revised text as well as remapping content to the EIA-748-E Guidelines and applicable government guides such as the DoD’s updated EVMSIG. Take the time to determine whether the documented processes make sense. If project personnel are ignoring the current process, it may be an indication it needs a revisit; it may need to be simplified or redone.
Consider reviewing the schedule data quality assessment process. Are project schedules providing an accurate forecast of the time required to complete the remaining work effort? This includes assessing whether task duration estimates are realistic as discussed in another blog, Improving IMS Task Duration Estimates. The IMS is the first line of defense to identify the potential that a cost overrun issue is likely to occur.
Lastly, open communication is essential to ensure technical, schedule, or cost realized risks are visible to all stakeholders. What is certain in any project plan is that things will not go as planned. Success depends upon quickly identifying the root cause of an issue and correcting course to reduce or eliminate the impact.
Reminder of the Objective of the ETC/EAC
The ETC is the detailed step-by-step plan the CAM provides to show how the remaining work will be accomplished. The goal of maintaining a credible ETC and EAC is to verify an executable plan is being regularly updated to accomplish the remaining scope of work within the contract’s schedule, cost, and funding targets for internal management visibility and control. The customer must also have confidence in the contractor’s ability to deliver and meet the remaining contract objectives.
The best way to prevent an ETC/EAC process CAR is to ensure you have a useful established process personnel follow, and they know how to use the schedule and cost tools to consistently maintain quality schedule as well ETC and EAC data. H&A scheduling and earned value consultants have worked with numerous clients to design or enhance their ETC/EAC process. H&A also offers EVMS training workshops that include content on how to develop a realistic EAC. Regular EVMS training always helps to reinforce best practices. Call us today at (714) 685-1730 to get started.
Humphreys & Associates has posted a 2020 update to the series of blogs discussing the DCMA Compliance Review (CR) process. “Compliance Review” is the term used for the formal EVM System review DCMA performs to determine a contractor’s compliance with the EIA-748 Standard for EVMS guidelines. This can also include, as applicable, Surveillance Reviews and Reviews for Cause (RFC).
DCMA used to follow a 16 Step compliance review process. This changed to an 8 Step process with the release of the DCMA Instruction 208 (DCMA-INST 208) titled “Earned Value Management System Compliance Reviews Instruction.” This Instruction has been rescinded and replaced with a set of DCMA Business Practices (BP). These Business Practices split out topics that the old DCMA Instruction 208 covered in one document. Whether you are a contractor new to the EVM contracting environment or a seasoned veteran, if the Earned Value Management System (EVMS) compliance and acceptance authority is the Defense Contract Management Agency (DCMA), these new Business Practices apply to you.
The four updated blogs include:
EVMS Compliance Review Series #1 – Prep for the DCMA Compliance Review Process. This blog presents the set of DCMA Business Practices (BP) that define the EVMS and Review process and specifically discusses Business Practice 6 “Compliance Review Execution.” It also discusses what you can expect should you need to complete the DCMA Compliance Review process through the 5 phases and 23 Steps outlined in BP6. It is critical you are able to complete each step in the process successfully the first time through to prevent delays. The best way to make sure you are prepared is to conduct one or more internal EVMS Mock Reviews, the topic for the next blog.
EVMS Compliance Review Series #2 – Conducting Internal Mock Reviews (Self Assessments). This blog discusses the importance of conducting a thorough internal review of your EVMS. You may or may not have the expertise in-house to conduct this simulation of a Compliance Review. An independent third party can help you prepare for a DCMA compliance review. The objective is to conduct the EVMS Mock Review to simulate everything DCMA will do. DCMA also expects a thorough scrub of the schedule and cost data – data traceability and integrity is essential.
EVMS Compliance Review Series #3 – Using Storyboards to Depict the Entire EVMS. Do you need a refresher on the role of storyboards in a compliance review? Storyboards can make a difference in training your personnel and explaining to the DCMA personnel how your EVMS works. Storyboards can take many forms, and if you don’t have one in place, consider starting with the flow diagrams in your EVM System Description.
EVMS Compliance Review Series #4 – Training to Prepare for Interviews. This blog highlights the importance of conducting training for your personnel, particularly the control account managers (CAMs), so they are able to complete successful interviews with DCMA personnel. H&A recommends completing a three step training process to proactively address any issues.
Help Preparing for a Compliance Review
Do you need help preparing for a DCMA compliance or surveillance review? Download the set of DCMA Business Practices and read our updated blogs so you have an idea of what is ahead. Humphreys & Associates can help you conduct a Mock EVMS Review, perform a data quality assessment, create a storyboard, or conduct EVMS interview training and mentoring for your personnel. Call us today at (714) 685-1730 or email us.