Revisions

Formal Reprogramming: OTB or OTS Best Practice Tips

, , , ,
Formal Reprogramming: OTB or OTS Best Practice Tips

As a result of an Earned Value Management System (EVMS) compliance or surveillance review, the Defense Contract Management Agency (DCMA) or DOE Office of Project Management (PM-30) may issue a corrective action request (CAR) to a contractor. H&A earned value consultants frequently assist clients with developing and implementing corrective action plans (CAPs) to quickly resolve EVMS issues with a government customer.

A recent trend our earned value management consultants have observed is an uptick in the number of CARs being issued related to over target baselines (OTB) and/or over target schedules (OTS). On further analysis, a common root cause for the CAR was the contractors lacked approval from the contracting officer to implement the OTB and/or OTS even though they had approval from the government program manager (PM).

So why was a CAR issued?  It boils down to knowing the government agency’s contractual requirements and EVMS compliance requirements.

What is an OTB/OTS and when it is used?

During the life of a contract, significant performance or technical problems may develop that impact schedule and cost performance. The schedule to complete the remaining work may become unachievable. The available budget for the remaining work may become decidedly inadequate for effective control and insufficient to ensure valid performance measurement. When performance measurement against the baseline schedule and/or budgets becomes unrealistic, reprogramming for effective control may require a planned completion date beyond the contract completion date, an OTS condition, and/or a performance measurement baseline (PMB) that exceeds the recognized contract budget base (CBB), an OTB condition.

An OTB or OTS is a formal reprogramming process that requires customer notification and approval. The primary purpose of formal reprogramming is to establish an executable schedule and budget plan for the remaining work. It is limited to situations where it is needed to improve the quality of future schedule and cost performance measurement. Formal reprogramming may be isolated to a small set of WBS elements, or it may be required for a broad scope of work that impacts the majority of WBS elements.

Formal reprogramming should be a rare occurrence on a project and should be the last recourse – all other management corrective actions have already been taken. Typically, an OTB/OTS is only considered when:

  • The contract is at least 35% complete with percent complete defined as the budgeted cost for work performed (BCWP) divided by the budget at completion (BAC);
  • Has more than six months of substantial work to go;
  • Is less than 85 percent complete; and
  • The remaining management reserve (MR) is near or equal to zero.

A significant determining factor before considering to proceed with a formal reprogramming process is the result from conducting a comprehensive estimate at completion (CEAC) where there is an anticipated overrun of at least 15 percent for the remaining work.

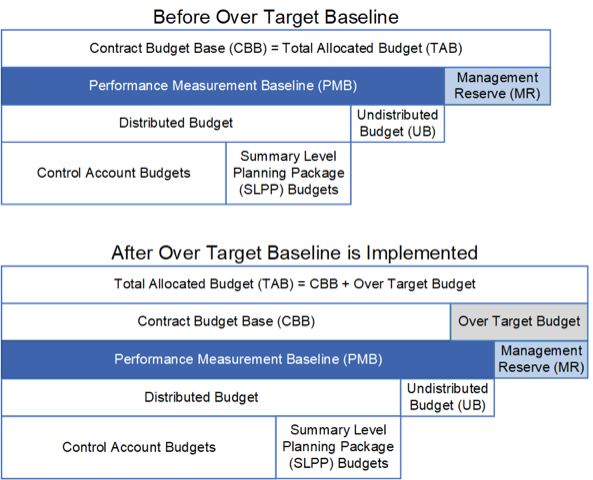
When an OTB is approved, the total allocated budget (TAB) exceeds the CBB, this value referred to as the over target budget. Figure 1 illustrates this.

Before Over Target Baseline
Figure 1 – Over Target Baseline Illustration

When an OTS is approved, the same rationale and requirements for an OTB apply. The planned completion date for all remaining contract work is a date beyond the contract completion date. The purpose of the OTS is to continue to measure the schedule and cost performance against a realistic baseline. The process must include a PMB associated with the revised baseline schedule. Once implemented, the OTS facilitates continued performance measurement against a realistic timeline.

Contractual Obligations

An OTB does not change any contractual parameters or supersede contract values and schedules. An OTS does not relieve either party of any contractual obligations concerning schedule deliveries and attendant incentive loss or penalties. An OTB and/or OTS are implemented solely for planning, controlling, and measuring performance on already authorized work.

Should you encounter a situation where it appears your best option is to request an OTB and/or OTS, the DoD and DOE EVMS policy and compliance documents provide the necessary guidance for contractors. It is imperative that you follow agency specific guidance to prevent being issued a CAR or your OTB/OTS request being rejected.

DoD and DOE both clearly state prior customer notification and contracting officer approval is required to implement an OTB and/or OTS. These requirements are summarized the following table.

ReferenceDoD/DCMA1DOE
RegulatoryDFARS 252.234-7002 Earned Value Management System
“(h) When indicated by contract performance, the Contractor shall submit a request for approval to initiate an over-target baseline or over-target schedule to the Contracting Officer.”
Guide 413.3-10B Integrated Project Management Using the EV Management System
6.1.2 Contractual Requirements.
“…if the contractor concludes the PB TPC and CD-4 date no longer represents a realistic plan, and an over-target baseline (OTB) and/or over-target schedule (OTS) action is necessary. Contracting officer approval is required before implementing such restructuring actions…”
Attachment 1, Contractor Requirements Document
“Submit a request for an Over-Target Baseline (OTB) or Over-Target Schedule (OTS) to the Contracting Officer, when indicated by performance.”
EVMS Compliance2Earned Value Management System Interpretation Guide (EVMSIG)3
Guideline 31, Prevent Unauthorized Revisions, Intent of Guideline
“A thorough analysis of program status is necessary before the consideration of the implementation of an OTB or OTS. Requests for establishing an OTB or an OTS must be initiated by the contractor and approved by the customer contracting authority.
EVMS Compliance Review Standard Operating Procedure (ECRSOP), Appendix A, Compliance Assessment Governance (CAG)
Subprocess G. Change Control
G.6 Over Target Baseline/Over Target Schedule Authorization
“An OTB/OTS is performed with prior customer notification and approval.”
See Section G.6 for a complete discussion on the process.
Contractor EVM SD4DCMA Business Process 2  Attachment, EVMS Cross Reference Checklist (CRC), Guideline 31.
“b. Are procedures established for authorization of budget in excess of the Contract Budget Base (CBB) controlled with requests for establishing an OTB or an OTS initiated by the contractor, and approved by the customer contracting authority?”
DOE ESCRSOP Compliance Review Crosswalk (CRC), Subprocess Area and Attribute G.6
“Requests for establishing an OTB or an OTS are initiated by the contractor and approved by the customer contracting authority.”

Notes:

  1. When DoD is the Cognizant Federal Agency (CFA), DCMA is responsible for determining EVMS compliance and performing surveillance. DCMA also performs this function when requested for NASA.
  2. Along with the related Cross Reference Checklist or Compliance Review Crosswalk, these are the governing documents the government agency will use to conduct compliance and surveillance reviews.
  3. For additional guidance, also see the DoD EVM Implementation Guide (EVMIG) , Section 2.5 Other Post-Award Activities, 2.5.2.4 Over Target Baseline (OTB) and Over Target Schedule (OTS). The EVMIG provides more discussion on the process followed including the contractor, government PM, and the contracting authority responsibilities.
  4. Your EVM System Description (SD) should include a discussion on the process used to request an OTB/OTS. The EVM SD content should be mapped to the detailed DCMA EVMS guideline checklist or the DOE Compliance Review Crosswalk (subprocess areas and attributes) line items.

Best Practice Tips

The best way to avoid getting a CAR from a government agency related to any OTB or OTS action is to ensure you have done your homework.

  • Verify your EVM SD, related procedures, and training clearly defines how to handle this situation. These artifacts should align with your government customer’s EVMS policy and regulations as well as compliance review guides, procedures, and checklists. Be sure your EVM SD or procedures include the requirement to notify and gain approval from the government PM and contracting officer, as well as what to do when the customer does not approve the OTB or OTS. Also discuss how to handle approving and managing subcontractor OTB/OTS situations; the prime contractor is responsible for these actions. Your EVMS training should also cover how to handle OTB/OTS situations. Project personnel should be aware of contractual requirements as well as your EVMS requirements and be able to demonstrate they are following them.
  • Maintain open communication with the customer. This includes the government PM as well as the contracting officer and any other parties involved such as subcontractors. Requesting an OTB or OTS should not be a surprise to them. Verify a common agreement has been reached with the government PM and contracting officer that implementing an OTB or OTS is the best option to provide visibility and control for the remaining work effort.
  • Verify you have written authorization from the government PM and the contracting officer before you proceed with implementing an OTB or OTS. You will need this documentation for any government customer EVMS compliance or surveillance review. Your baseline change requests (BCRs) and work authorization documents should provide full traceability for all schedule and budget changes required for the formal reprogramming action.

Does your EVM SD or training materials need a refresh to include sufficient direction for project personnel to determine whether requesting an OTB or OTS makes sense or how to handle OTB/OTS situations? H&A earned value consultants frequently help clients with EVM SD content enhancements as well as creating specific procedures or work instructions to handle unique EVMS situations. We also offer a workshop on how to implement an OTB or OTS .  Call us today at (714) 685-1730 to get started.

Formal Reprogramming: OTB or OTS Best Practice Tips Read Post »

EIA 748-D Released – Change Notes

,

EIA 748 D Released

Portions extracted from the EIA-748-D © SAE International (with permission).

Are you aware that a revision to the Society of Automotive Engineers (SAE) / Electronics Industry Alliance (EIA)  Standard 748 Earned Value Management Systems, has been released? The new revision is SAE / EIA 748-D. Officials have been discussing the changes at recent industry conferences.

Sections 2.1-2.5 – No Changes to EVMS Guidelines

No changes have been made to the 32 EVMS Guidelines in Sections 2.1-2.5 of the standard. The changes are primarily clarifications of the existing text:

Section 1 – Additional 4th Note

Section 1 “Scope of EVMS” previously “Introduction” in 748-C now has an additional 4th Note:

“Note 4: There are occasions where it is beneficial for complementary systems or methodologies (e.g., Enterprise/ Manufacturing Resource Planning, Agile Software Development, Theory of Constraints) to interface with the EVM System. These complementary systems or methodologies can be used to deliver functionality and value to the customer while EVM provides a standardized method for measuring progress and reporting across the contract. The EVMS documentation should describe the interface content as well as the recurring control process to maintain data conformance and system compliance.” © SAE

Section 2.6 –  Six Additional Terms

Section 2.6 “Common Terminology” includes six additional terms:

ACTIVITY OR TASK: An element of work with an expected duration in the network schedule that is performed during the course of a project. Activities generally have expected resource requirements used to determine the budget for the work effort. One or more activities may relate to a work package.

AUTHORIZED UNPRICED WORK (AUW): A contract scope change which has been directed by the customer’s contracting officer but has not yet been fully negotiated/definitized. It includes a value, excluding fee or profit, typically associated with the authorized, unpriced change order.

ELEMENT OF COST (EOC): The categories of cost such as labor, material, subcontractor, and other direct costs as defined by company accounting practices.

OVER TARGET SCHEDULE (OTS): A replanned schedule baseline that extends beyond contract milestone dates, delivery dates, or completion date. An OTS is usually accompanied by an increase in budgets resulting in a corresponding Over Target Baseline (OTB). It typically requires customer approval to implement.

RISK AND OPPORTUNITY (R&O): An uncertain future event or situation that could impact the ability to achieve overall project requirements within defined cost, schedule, and technical objectives. Risk has two components: (1) the probability (or likelihood) of a particular outcome and (2) the consequences (or impact) of that outcome. The consequences of risks are typically thought of as negative that may need to be mitigated to minimize the impact to the project. A risk event with positive consequences is referred to as an opportunity that may be captured as a benefit to the project.

SUMMARY LEVEL PLANNING PACKAGE (SLPP): An aggregation of far-term work efforts (scope, schedule, and budget) that are not able to be identified at the control account level but can be distributed to reporting level WBS elements.

Section 2.6 – Term Changes

Section 2.6 “Common Terminology” includes changes/clarifications to existing terms:

ESTIMATE AT COMPLETION (EAC): The current estimated total cost for authorized project work. It equals the cumulative to date Actual Cost of Work Performed (ACWP) plus the estimated costs to complete (Estimate to Complete or ETC) the authorized work remaining.

LEVEL OF EFFORT (LOE): Support type activities that lack measurable output or product that cannot be discretely planned or objectively measured in a practical manner. LOE automatically earns performance with the passage of time, an earned value technique.

MANAGEMENT RESERVE (MR): An amount of the total budget set aside for unplanned, in scope effort that may arise during the course of the project which cannot be identified in advance and is used to handle execution risks. Management reserve budget should be commensurate with the level of project risk. It is not part of the Performance Measurement Baseline (PMB).

OVER-TARGET BASELINE (OTB): A Performance Measurement Baseline (PMB) that exceeds the Contract Budget Base (CBB). It is implemented to produce a realistic schedule and budget plan for the project’s remaining work. It typically requires customer approval to implement.

Section 2.7 – 3 Additional References

Section 2.7 “List of Suggested References” has been updated to include 3 additional references. The complete list is below:

– NDIA IPMD EVMS Intent Guide
– NDIA IPMD IBR Guide
– NDIA IPMD Surveillance Guide
– NDIA IPMD EVMS Acceptance Guide
– NDIA IPMD EVMS Application Guide
– NDIA IPMD Planning and Scheduling Excellence Guide (PASEG)
– NDIA IPMD Industry Practice Guide for Agile on Earned Value Management Programs (New)
– NDIA IPMD Master Definitions List for IPMD Guides (New)
– NDIA IPMD Earned Value Management System Guideline Scalability Guide (New)

Sections 3 thru 5

In Section 3.2.1 WBS Dictionary, discussion regarding segregation by WBS element for direct costs has been removed.

In Section 3.3.1 Control Accounts, discussion regarding guidance that a Control Account shall not span multiple WBS elements has been removed.

In Section 3.3.1, a new figure, Figure 1 – Establishing Control Accounts was added.

In Section 3.4.3 Subcontract/Procurement Schedules, the phrase “high risk” has been removed.

In Section 3.8.2 Cost Performance, The Labor Rate and Efficiency variance calculations were corrected. The corrected equations are below.

• Labor Rate Variance Calculation = Actual Hours x (Earned Rate – Actual Rate)
• Efficiency Variance Calculation = Earned Rate x (Earned Hours – Actual hours)

In Section 3.8.2 Cost Performance, the acronym “EAC” has been replaced with “ETC”.

In Section 3.10.2 Authorized Changes, discussion regarding allowable changes for optimum utility has been removed.

In Section 4 System Documentation, the term “GEIA” has been replaced with “SAE”.

In Section 5.1, Evaluation Process, the term “officer” has been replaced with “authority”.

In summary, EIA 748-D has added/modified a few items for clarification but does not change any of the implementation, reporting, surveillance, or enforcement aspects of Earned Value Management Systems.

Purchase a copy of the standard here: https://www.sae.org/standards/content/eia748d/

EIA 748-D Released – Change Notes Read Post »

Confusing QBD Baseline Changes with QBD EAC Changes

, , , ,

Historic Battleship Engine Room

Quantified Backup Data

Quantified Backup Data (aka QBD) has become a requirement for contractors who make use of the “Percent Complete” Earned Value Technique (EVT). This requirement is actually a good thing because it helps eliminate the guesswork previously cited as a flaw in the percent complete EVT. Unfortunately, it has become a good idea gone bad through over-implementation.

The primary problem: Confusing “QBD Baseline Changes” with “QBD EAC Changes.” Many contractors are unnecessarily bogging down their change control process with requests to “change the QBD” when all that is really changing is the detail behind some of the steps in the QBD.

The Cake Example

Let’s take a simple, practical example of baking a cake to illustrate the difference. What follows is an approach found online from one baking company. The example weights have been added by the author.

10 Basic Steps to Making Any Cake Step Weight (Percentage of Process)
1.     Select the recipe for the type of cake 2%
2.     Select and prepare (grease) the pans 2%
3.     Preheat the oven 2%
4.     Prepare the ingredients 30%
5.     Mix the ingredients 40%
6.     Put batter in pan and bake the cake 5%
7.     Remove the cake from the pan 2%
8.     Let the cake cool 2%
9.     Make the frosting 10%
10.  Frost the cake 5%

For the context of this blog, this bakery’s approach IS the Cake (baseline) QBD. Chocolate cake, pound cake, apple cake, one layer cake, multi-tiered cake, birthday cake, or wedding cake. It does not matter. This bakery approaches making any type of cake with this QBD. Some cakes, however, are more complex than other cakes – not all cakes are created equal.

Steps 1, 2, 3, 6, 7, and 8 are standard and would likely have the same “budget weight” in the Cake QBD, regardless of the type of cake. Steps 4, 5, 9, and 10, on the other hand, might be more involved for a complex cake. Remember: Complexity does not change the Cake (baseline) QBD!

Simple Cake vs Complex Cake

Let’s look at the Cake QBD to see how different types of cakes are handled by comparing a Simple Cake, Vanilla with Chocolate Frosting, to a Complex Cake, Apple Walnut German Chocolate.

Follow Steps 1, 2, and 3 (unchanged)

Step 4: Prepare the ingredients

Simple Cake: Gather eggs, milk, flour, cake batter mix.

Complex Cake: Gather eggs, milk, flour, sour cream, walnuts, apples, coconut, lemon juice, pre-cooked apples, chopped walnuts, shaved coconut.

Step 5: Mix the ingredients

Simple Cake: Blend together the eggs and milk. Then add in the flour and dry cake batter mix.

Complex Cake: Blend together the eggs and milk. When smooth, fold in sour cream. Then add in the flour and the cake batter mix. When thoroughly blended, add cooked apples, lemon juice, chopped walnuts, and shaved coconut. Blend until evenly mixed.

Follow Steps 6, 7, and 8 (unchanged)

Step 9: Make the frosting

Simple Cake:  Pre-made chocolate frosting mix.

Complex Cake:  German chocolate frosting mix, add coconut, add chopped walnuts, mix gently until additions are evenly spread throughout mix.

Step 10:  Frost the cake

Simple Cake:  Frost between layers, frost top layer, frost side of cake.

Complex Cake: Frost between layers, frost top layer, frost side of cake. Apply apple wedges on top of the frosted layer, sprinkle on more chopped walnuts, apply frosting flowers around bottom with frosting tool.

As you can see, the 10 Step Cake QBD did not change throughout this process. What did change was the set of ingredients and some of the added lower level steps within the QBD Steps 4, 5, 9, and 10. This might add some cost (EAC) for the added ingredients, and for the additional labor of precooking, chopping, and shaving. However, in the overall context of the Cake Baking process, the steps (QBDs) and the associated weighting of each QBD remained the same. In this bakery, all that changes would be the forecast cost (EAC) for the complex cake over the simple one – i.e., no baseline change request (BCR) is needed to change the QBD!

QBD vs EAC

In this simple example, the QBD is Baking a Cake. It is not “Baking an Apple Walnut German Chocolate Cake.” If this were the QBD, then this bakery would have hundreds of QBDs, depending on the different types and complexities of cakes the bakery could possibly make. For example, would you want a separate QBD for a birthday cake to say “Happy Birthday Johnny”? No, that would be a cost (EAC) for the Frosting QBD Step. The QBD EACs affected would be Step 9, Make the frosting, and Step 10, Frost the cake. Rather than hundreds of QBDs, this bakery has ONE! The cost (EAC) of a cake varies based on the complexity and content of the cake.

This QBD approach applies to any number of other processes. Here are a couple of others:

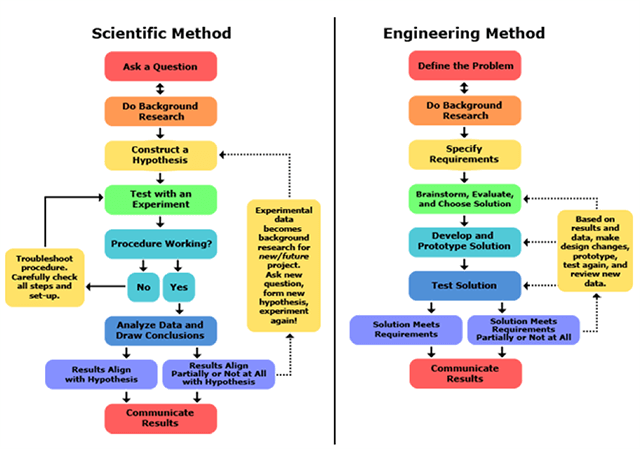
Flowchart Showing the difference and similarities of the scientific and engineering methods.

Above: Basic idealized steps of the scientific method (left) and engineering design process (right).

*From sciencebuddies.org

In this case, the complexity of the problem being addressed might impact the amount of research required or the experiments or brainstorming solutions needed. This could dictate the number of times the yellow box to the right (the re-do box) is required. However, the approach is exactly the same until the process achieves the “Results Align with Hypothesis” (for the scientific method) or the “Solution Meets Requirements” (for the engineering design method), and the results are communicated.

The House Example

Another practical hands-on example could be the steps in building a house:

  1. Grading and site preparation
  2. Foundation construction
  3. Framing
  4. Installation of windows and doors
  5. Roofing
  6. Siding
  7. Electrical Rough-In
  8. Plumbing Rough-In
  9. HVAC Rough-In
  10. Insulation
  11. Drywall
  12. Trim
  13. Painting
  14. Finish electrical
  15. Bathroom and kitchen counters and cabinets
  16. Finish plumbing
  17. Carpet and flooring
  18. Finish HVAC
  19. Hookup to water main, or well drilling
  20. Hookup to sewer or installation of a septic system
  21. Punch list

As with baking a cake, for this builder, the size of the house will make a difference in how much the house will cost, but the QBD approach to building each house is the same. Some of the lower level activities below each QBD step might be more involved. For example, Step 2, Foundation construction might be more involved if the house is to have a basement. Other steps might be more or less involved. Step 17, Carpet and flooring might stop at the concrete slab because the buyers want to have their own custom flooring and carpeting put in later. None of these examples change the 21 QBDs this contractor follows when building a house. The lower level activities will simply cost more or less than other models (the EAC – not the baseline QBD), but the overall weighting of the QBDs for “Building a House” would be the same.

The Scope Has Not Changed

The same approach can be used for engineering drawings, conducting inspection testing, developing a drug for FDA approval, a scientific approach to a health problem, or any other process that follows a standardized approach toward its end product. The key is segregating the EAC aspect from the baseline QBD aspect of the process. Don’t get mired in constantly trying to “change the QBD” when it is not needed.

If the basic steps do not change, the QBD is not changing! More or less granularity in the lower level details beneath each QBD step is handled in EAC space and will be reflected in the cost of the task. You do not need to change the budget. Why? Because the scope has not changed.

Repeat with emphasis. THE SCOPE HAS NOT CHANGED – you are still:

  • Doing an engineering drawing,
  • Resolving a scientific or engineering design problem,
  • Building a house, or even just
  • Baking a cake.

Let’s keep QBDs simple for the CAMs – and keep the change control process uncluttered.

Humphreys & Associates can help with your QBD planning and implementation. Contact us at (714) 685-1730 or email us.
Confusing QBD Baseline Changes with QBD EAC Changes Read Post »

Scroll to Top