A common Earned Value Management System (EVMS) compliance and surveillance review finding are issues with a contractor’s estimate at completion (EAC) process. A credible EAC is essential to successfully manage all contracts and projects.
EACs are important because they provide a projection of the cost at contract or project completion, which is also an estimate of total funds required by the customer. It matters because EACs represent real money. When the most likely EAC exceeds the negotiated contract cost, the contractor’s profit margins may be at risk. It also creates a problem for the customer when the most likely EAC exceeds their funding limits.
We recently updated our blog titled Maintaining a Credible Estimate at Completion (EAC) to highlight why this is a good time to review and potentially update your estimate to complete (ETC) and EAC processes. The updated blog added content specific to:
Incorporating integrated master schedule (IMS) analysis to test the realism of the EAC to identify any disconnects with the cost-based independent EACs (IEACs). It is equally important to determine a realistic forecast completion date (FCD).
Ensuring control account managers (CAMs) are in a position to substantiate their schedule timeline, resource requirements, and cost estimate to complete the remaining work. It is equally important that project managers proactively take the action of “scrubbing” the CAM’s detail ETC/EAC and verifying the data to gain a better understanding of the project’s current state. This improves the quality of the project-level forecast completion date as well as the range of project-level EACs.
Suggested actions to review and enhance current processes from basic steps, such as incorporating an analysis of the IMS Current Execution Index (CEI) to gain an understanding of how well project personnel can forecast into the future, and taking advantage of AI tools to provide additional data analysis insight.
In addition, the publication of the EIA-748-E Standard for EVMS revised 27 guidelines and related updates to government agency guidance such as the DoD EVMS Interpretation Guide (EVMSIG) will require contractors to review and remap EVM System Description content to the revised set of guidelines. The updated blog emphasizes this is a good time to revisit internal ETC/EAC processes and procedures to determine where improvements can be made as well as to ensure project personnel are following the documented processes. The EIA-748-E split the EIA-748-D Guideline 27 into two guidelines. The EIA-748-E Guideline 20 is specific to the control account level EACs and Guideline 23 is specific to the project level EACs. An EVM System Description should have content specific to the process at the control account level as well as the project level that can easily be mapped to the EIA-748-E Guidelines 20 and 23.
Do Your Internal Processes and Procedures Need a Refresh?
H&A earned value consultants routinely assist contractors with updating their internal processes and procedures to reflect the evolving EVMS requirements and guides, regulatory environment, and toolset capabilities. Workflow steps can often be simplified and the quality of performance analysis can be improved with a refreshed approach that reduces the time needed to produce reliable and actionable information. Call us today at (714) 685-1730 to get started.
I have read several Earned Value Management (EVM) reports, papers, and articles that debate what company organization should “own” EVM and the company’s Earned Value Management System (EVMS). These debates most often mention the finance department and program organization as common EVM “owners.” The majority opinion seems to be that because EVM is a program management best practice it belongs in the program organization. A minority opinion is that because EVM is denominated in dollars, schedule included, and because EVM reports are financial in nature, EVM belongs in the finance department. Before we dive into this debate, a summary of the responsibilities of a Chief Financial Officer (CFO) and the head of programs is useful. In the Company A and Company B examples to follow, both the CFO and the head of programs reported to the company president.
What are the duties of a Chief Financial Officer (CFO)?
A CFO has three duties; each measured in the time domain. The first duty of the CFO is as the company’s controller and is responsible to accurately and honestly report past company financial performance. The CFO is also responsible for the current financial health of the company – to ensure that today’s decisions create rather than destroy value. And lastly, the CFO must protect the company’s future financial health and that all expenditures of capital maximize that future financial health. Every business decision, especially those of the CFO, are either good decisions (are accretive – increase shareowner value) or are bad decisions (are dilutive – destroys shareowner value).
What are the duties of the Head of Programs?
The head of programs is typically a Vice President or higher and all program and project managers report to them. The head of all programs has profit and loss responsibility for their portfolio of programs and projects. In addition, each program and project manager is responsible for achieving the technical, schedule, and cost requirements of the contracts they are executing on behalf of the company’s customers.
A Tale of Two Companies
I have first-hand experience with two companies and how each company decided who should “own” EVM that illustrates the nuances to these two approaches.
Company “A” had EVM assigned to the finance department. All EVM employees were overhead, even those assigned to a program. A new CFO arrived and quickly decided to reduce indirect costs, declaring that he was “coin-operated.” The new CFO terminated the employment of all EVM employees. Each program attempted to create an EVM branch office but failed. DCMA issued a Level 3 Corrective Action Request (CAR) detailing the EVMS deficiencies and the CFO was fired. A second new CFO arrived and agreed to transfer EVM to the head of programs. The head of programs was instrumental in changing the disclosure statement making EVM personnel assigned to a program a direct charge to that program or contract. The head of programs created a Program Planning and Control (PP&C) organization and demanded all Program Managers and their program members to quickly learn, use, and master EVM. A program control room was built with five screens. Daily 2 pm EVM data-driven reviews were held on short notice. These daily reviews became known as “CAM Bakes.” The EVM and program management culture changed quickly and dramatically at Company “A.”
Company “B” had EVM assigned to the CFO who was as “coin-operated” and unaware of EVM as was the first new CFO of Company “A.” The culture of company “B” was very hostile to EVM, so it probably did not matter who “owned” EVM. The company failed 16 of the EIA-748 Standard for EVMS 32 guideline requirements and they lost their DCMA approved EVMS status. Significant withholdings were imposed and the company’s reputation was damaged. Several top managers hostile to EVM sought employment elsewhere. A new CFO arrived who was also coin-operated – with one difference – the CFO was an expert in EVM. The new CFO formed a partnership with the head of programs. The new CFO was as much a program manager as he was a CFO. The new CFO told his direct reports assigned to each program to “make the program managers successful.” And they did exactly that.
The new CFO understood that the company was the sum of all its contracts and that every dollar flowed from its customers. The EVM and program management culture at Company “B” changed rapidly.
Who Should “Own” EVM? Programs or Finance?
Returning to our original question of who should “own” EVM, the majority theory is that the program organization should “own” EVM. All else being equal, I tend to agree with this theory.
However, while theory is suggestive, experience is conclusive. My experience at Company “A” proved that a strong program leader could rapidly change the EVM and program management culture of a company. My experience at Company “B” proved that a CFO could “own” EVM and be successful at changing the company’s EVM and program management culture. The CFO and the head of programs must form an EVM partnership no matter who “owns” EVM.
Who “owns” EVM at your company?
Mr. Kenney is a senior business executive with over 35 years of experience in the aerospace industry as well as over 10 years as a consultant to industry. He is an experienced practitioner of program management best practices as an Executive Vice President of Government Programs, Vice President of Naval Programs, and Program Manager at various aerospace and defense contractors. He is also a retired U.S. Marine Corps Colonel with 27 years of active and reserve duty.
Originally published March 2023 | Revised May 13, 2026
Quick Summary
EVMS compliance and surveillance reviews continue to identify issues related to poor-quality estimates at completion (EAC), underscoring the need for credible EACs to support effective project management, financial integrity, customer confidence, and funding decisions.
Credible EACs require actively maintained, data-driven estimates to complete (ETCs) that integrate schedule, resource, cost, and risk information along with regular management realism assessments and open communications with all stakeholders.
Organizations can improve EAC credibility by avoiding management imposed targets, keeping schedule and cost systems aligned, routinely reviewing the quality of the ETC data, leveraging evolving tools and analytics, and updating processes to align with the revised EIA-748-E guidelines.
The Defense Contract Management Agency (DCMA) as well as other government entities responsible for Earned Value Management System (EVMS) compliance and surveillance continue to identify issues with the quality of contractor estimates at completion (EAC). Using DCMA statistics, EIA-748-D Guideline 27, Maintain Estimates at Completion, is one of three guidelines1 that represent a third of all EVMS Corrective Action Requests (CARs).
Why Credible EACs Matter
A credible EAC is essential to all stakeholders and a foundation for managing projects successfully. Executive management and project managers must have a complete and accurate understanding of the projected contract or project EAC to ensure financial data is not misrepresented (Sarbanes-Oxley). The customer must have confidence in a contractor’s forecast completion date (FCD) and EAC data to understand whether the remaining work can be completed within the contractual period of performance and target cost, or, if not, how long it will take and how much it will cost.
When the most likely EAC exceeds the negotiated contract cost, the contractor’s profit margins may be at risk. Should the most likely EAC exceed the customer’s funding limit, they will need to secure additional funding, modify the work scope, or slow the pace of the project. No one likes schedule or cost surprises.
What determines whether an EAC is credible?
A credible EAC reflects the cumulative to date actual costs of work performed (ACWP) (costs the contractor has already incurred) plus the current ETC. The ETC must provide a realistic estimate of the time and resources required to complete the remaining authorized work using projected rates. It represents the time phased estimate of spending which translates to the future funds required.
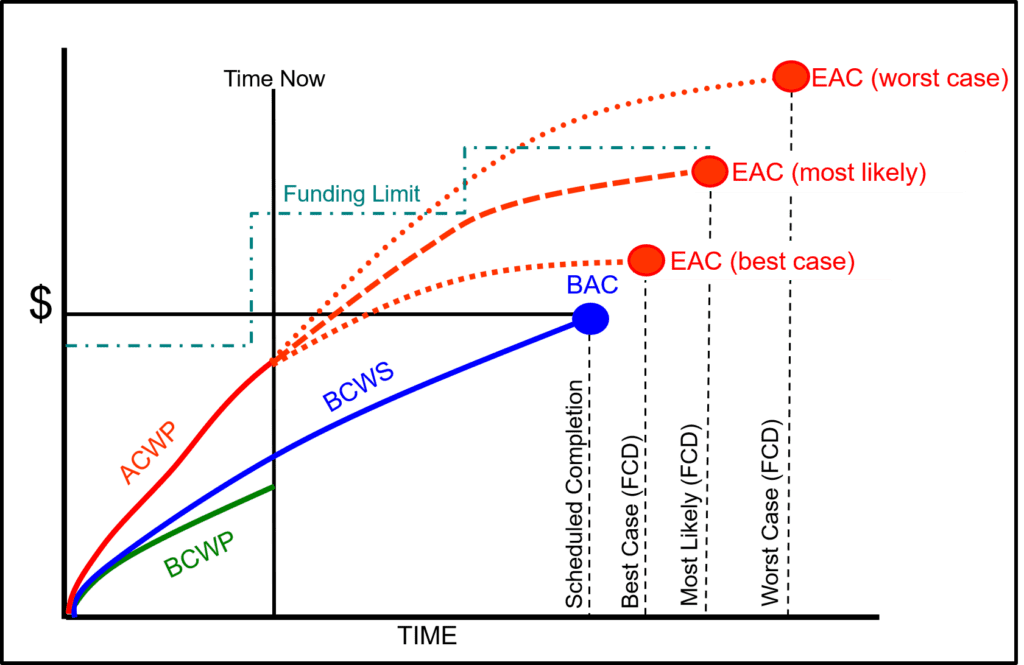
EACs should be based on actual costs and performance to date, the nature and amount of remaining scope, assumptions about and projections of future performance for that scope, risks and opportunities, economic escalation, expected direct and indirect rates, subcontract, and material commitments. As illustrated in Figure 1, project managers should routinely evaluate their project’s ACWP, ETC, and range of EACs along with the funding profile to verify amounts expended and forecasted are within the parameters of available contract funds.
Figure 1: Range of Project EACs with Funding Profile
What project control practices help to ensure EACs are realistic?
Three recommended best practices include:
Actively maintaining the detail ETC data every reporting cycle. This starts with updating the current schedule to include all authorized remaining scope along with the resource loaded activities to reflect performance to date and the latest planning (timing and resource requirements) for work in progress and future work effort. This is the basis for updating the time phased cost estimate for in progress work packages that is added to the cumulative to date actual costs as well as the cost estimate for future work/planning packages. Subcontract forecasted schedules and cost must be included. The current schedule forecast dates and time phased cost estimate must be aligned. Actively maintaining the detail data ensures the current schedule and ETC data reflect the project’s current state. The control account managers (CAMs) can substantiate their ETC with relevant data for analysis and take action to address a significant variance at completion (VAC).
Actively monitoring project FCDs and EACs. Project managers that routinely maintain a range of data driven FCDs and EACs (best case, most likely, and worst case) are better prepared to verify the control account FCDs and EACs are realistic, realized risks have been handled, and emerging risks have been identified, assessed, and addressed. Experienced practitioners use various metrics such as comparing the Cost Performance Index (CPI) to the To Complete Performance Index (TCPI) to test the realism of the EAC. They also include a realism check of the baseline and current integrated master schedule (IMS) to identify any potential disconnects with the cost-based indices discussed in a previous blog, Incorporating IMS Information Directly into IEAC Formulas. Managers should scrub the detail ETCs to assess the quality of the estimates and verify the content of the backup data. A good understanding of the detail ETCs is necessary to produce credible project level EACs with crisp rationale and narratives provided to executive management and the customer.
Maintaining open communications with all levels of management, subcontractors, and the customer. The project manager is the main conduit to manage impacts to their project’s FCD and EAC such as when finance changes direct or indirect rates, there are changes in resource availability or a spike in material prices, or the customer modifies the work scope or funding. As a result, project personnel can quickly handle issues or project changes. Direct and open communications with executive management ensures there is a clear understanding of their project’s FCD and EAC.
What are some things to avoid?
H&A consultants often observe practices that negate the value of maintaining the ETC/EAC and can result in an EVMS corrective action request (CAR). The root cause often points to ad-hoc processes or corporate culture. Examples:
Management provides a target FCD and EAC number the CAMs must match. The ETC/EAC should be “the voice of the CAM”. The CAM is saying “if you give me these resources as scheduled, I can finish the job this way.” Any approach that does not respect the voice of the CAM can cause the ETC/EAC to be unrealistic or at least unsubstantiated. Giving the CAM “the date and number” increases the likelihood the FCD and ETC are unrealistic. There may be a valid reason for this directive as a management what-if exercise or to gain a deeper understanding of the situation. When done as a routine management strategy, it diminishes the value of the ETC data to manage the project’s remaining work and prevent cost overruns. The CAMs should be in a position where they can substantiate their schedule timeline, resource requirements, and cost estimate to complete the remaining work. Project managers should be in a position where they can verify the detail ETC/EAC data to establish a level of confidence in their project level EACs they provide to executive management and the customer.
Project personnel take the path of least resistance. This is often an indication of a lack of direction or an established process. They either do not create the ETC data or maintain it on a routine basis. In some instances, the CAMs manage their ETC data to avoid oversight. An old but valid saying is “the tall grass gets mowed” – the CAM purposely doesn’t raise their ETC to a value that would attract attention. Another troublesome approach is to set a cost management tool option to a static EAC; the CAM may manually update the EAC number quarterly at best. The result? The FCD and ETC data isn’t current; there is zero insight into potential emerging issues. DCMA or the customer can easily identify this when they analyze the time-phased ETC data in the Integrated Program Management Data and Analysis Report (IPMDAR) Contract Performance Dataset (CPD) submittal.
Schedule and cost are created/maintained separately. This often occurs when the schedule and cost tools are not kept in sync for the project’s duration. Significant effort may go into ensuring the data are in alignment to establish the performance measurement baseline (PMB). The IMS resource loaded activities are used as the basis for the time phased budget baseline in the cost tool. However, the ETC data in the current schedule may not exist or be actively maintained. Project personnel only maintain the ETC data in the cost tool and fail to verify it aligns with the current schedule activity forecast dates and resource requirements. It is not part of their routine status and analysis process every month.
Taking Action to Review and Enhance Current Processes
A simple step to start with is to use the IMS Current Execution Index (CEI). This is a useful measure of how well a team can forecast just a single month into the future. If a team cannot achieve a high accomplishment rate against just a one-month forecast, any longer-term ETC is questionable. Start simple and focus on improving the one-month accuracy then move on to longer periods. Build confidence in the team’s ability to see and manage the future.
Another basic step. Build time into the process for managers to scrub ETCs. Maybe it is not possible to scrub every control account ETC every reporting period, but a rotational approach where ETCs are scrubbed as often as possible will improve the ETC and improve the understanding of the ETCs.
Innovate. AI tools are rapidly becoming capable of assuming skilled roles such as project analysts and can yield valuable insight. Tools are already available that can evaluate variances and variance analysis reports (VARs). Poor quality analysis translates to poor quality ETCs. Take action that supports improved analysis.
At a higher level, with the publication of the EIA-748-E Standard for EVMS revised 27 guidelines along with the evolving regulatory environment discussed in a previous blog, Revitalizing Earned Value Management Systems, this is a perfect time to review current EVMS ETC/EAC processes. The EIA-748-E split the EIA-748-D Guideline 27 into two parts: EIA -748-E Guideline 20 focuses on the control account level EACs and Guideline 23 focuses on the project level EACs. The DoD EVMS Interpretation Guide (EVMSIG) for Revision E has been updated accordingly.
We recommend reviewing approved EVM System Descriptions to ensure existing content supports the EIA-748-E Guideline revised text as well as remapping content to the EIA-748-E Guidelines and applicable government guides such as the DoD’s updated EVMSIG. Take the time to determine whether the documented processes make sense. If project personnel are ignoring the current process, it may be an indication it needs a revisit; it may need to be simplified or redone.
Consider reviewing the schedule data quality assessment process. Are project schedules providing an accurate forecast of the time required to complete the remaining work effort? This includes assessing whether task duration estimates are realistic as discussed in another blog, Improving IMS Task Duration Estimates. The IMS is the first line of defense to identify the potential that a cost overrun issue is likely to occur.
Lastly, open communication is essential to ensure technical, schedule, or cost realized risks are visible to all stakeholders. What is certain in any project plan is that things will not go as planned. Success depends upon quickly identifying the root cause of an issue and correcting course to reduce or eliminate the impact.
Reminder of the Objective of the ETC/EAC
The ETC is the detailed step-by-step plan the CAM provides to show how the remaining work will be accomplished. The goal of maintaining a credible ETC and EAC is to verify an executable plan is being regularly updated to accomplish the remaining scope of work within the contract’s schedule, cost, and funding targets for internal management visibility and control. The customer must also have confidence in the contractor’s ability to deliver and meet the remaining contract objectives.
The best way to prevent an ETC/EAC process CAR is to ensure you have a useful established process personnel follow, and they know how to use the schedule and cost tools to consistently maintain quality schedule as well ETC and EAC data. H&A scheduling and earned value consultants have worked with numerous clients to design or enhance their ETC/EAC process. H&A also offers EVMS training workshops that include content on how to develop a realistic EAC. Regular EVMS training always helps to reinforce best practices. Call us today at (714) 685-1730 to get started.
I’ll answer this provocative question now. DCMA, local and headquarters, are an EVM contractor’s “friend” with remarkable, but not unlimited, patience. When required, DCMA can become the contractor’s “tough love” friend.
DCMA and the contractor share the same interests – successful contract performance. DCMA is part of a triad that includes the Government’s program team, the contractor’s program team and their DCMA counterparts.
The title “Defense Contract Management Agency” reminds me of “grilled cheese sandwich” – the recipe and the product are in the name – “contract management” leads to well managed contracts.
EAC Vignette – Part One:
Contractor A has learned that their collocated DCMA has concerns about the company’s EAC process and resulting declared EACs. The company has learned that a Level III CAR on GL # 27 is being considered. Contractor A’s senior management decides to replace their EVM Core Leader with “new blood” to improve the company’s “relationship” with DCMA and avoid a Level III CAR.
Contractor A’s new EVM leader meets with her team and with the program managers that have an EVM contractual requirement. Company A’s new EVM leader is told that DCMA’s EAC concerns are a new issue. The company’s new EVM leader asks to meet with her DCMA counterpart to discuss their GL # 27 concerns, and to present a draft of a Corrective Action Plan (CAP).
During the meeting with DCMA’s EVM leader she mentions that the EAC concerns were a surprise to the company. The company’s new EVM leader briefs her draft CAP to her DCMA counterpart.
After the draft CAP has been briefed, the DCMA EVM leader comments, “your draft CAP is a good start. After I have time to fully digest your draft CAP I will send my comments and suggestions. As for being surprised by our EAC concerns, here is a file with 3+ years of letters, emails, meeting minutes from DCMA to your company outlining our continuing and growing concerns with your company’s EAC process.”
EAC Vignette – Part Two:
DCMA issued a Level III Corrective Action Request (CAR) to the contractor and is considering withholdings as an incentive for the company to quickly improve their EAC processes.
As promised, the DCMA EVM leader sent the following note to the company’s new EVM leader:
“I sent your draft GL # 27 CAP to my team for their comments and recommendations. My team’s key recommendations are:
1). Identify the weaknesses in your existing EAC processes. For each weakness, identify a corrective action. As much as possible, “mistake proof” your new processes. You should consider a review of several 100% complete contracts, and “replay” those contracts month-by-month using your new EAC processes to test their effectiveness.
2). As noted in our CAR, the company is required to report progress on the Corrective Action Plan (CAP). You should treat your CAP as a program. At a minimum, you should have an IMS and use appropriate earned value techniques to measure progress.
3). A sister division in your parent corporation, has a very mature and effective EAC process. You should considering asking for their assistance as you develop your CAP and begin its execution.
4). If you have questions as you execute your CAP, please don’t hesitate to contact me. If I don’t know the answer to your question, I’ll find someone that does know the answer and will share it with you.”
Personal Observations:
Based on my 32 years as an employee of defense contractors, and 7 years in earned value consulting, I offer the following:
1). DCMA “local” knows your company much better than you might think.
2). DCMA “headquarters” has knowledge and insight into many companies. From DCMA’s website: “We are the independent eyes and ears of DoD and its partners, delivering actionable acquisition insight from the factory floor to the front line …. around the world.”
3). A CAR from DCMA informs the company of “what” needs corrected but not “how” to correct the issue. That said, DCMA knows what will or will not work. Maintain a dialogue with DCMA.
4). “Compliance” is a lower bound for performance. DCMA will not object if a company decides to improve well beyond mere compliance.
5). Please consider the possibility that what may appear to be a “new” problem for your company, may have already been solved by another company. Find who has already solved your “new” problem. Ask for help.
Humphreys & Associates has posted a 2020 update to the series of blogs discussing the DCMA Compliance Review (CR) process. “Compliance Review” is the term used for the formal EVM System review DCMA performs to determine a contractor’s compliance with the EIA-748 Standard for EVMS guidelines. This can also include, as applicable, Surveillance Reviews and Reviews for Cause (RFC).
DCMA used to follow a 16 Step compliance review process. This changed to an 8 Step process with the release of the DCMA Instruction 208 (DCMA-INST 208) titled “Earned Value Management System Compliance Reviews Instruction.” This Instruction has been rescinded and replaced with a set of DCMA Business Practices (BP). These Business Practices split out topics that the old DCMA Instruction 208 covered in one document. Whether you are a contractor new to the EVM contracting environment or a seasoned veteran, if the Earned Value Management System (EVMS) compliance and acceptance authority is the Defense Contract Management Agency (DCMA), these new Business Practices apply to you.
The four updated blogs include:
EVMS Compliance Review Series #1 – Prep for the DCMA Compliance Review Process. This blog presents the set of DCMA Business Practices (BP) that define the EVMS and Review process and specifically discusses Business Practice 6 “Compliance Review Execution.” It also discusses what you can expect should you need to complete the DCMA Compliance Review process through the 5 phases and 23 Steps outlined in BP6. It is critical you are able to complete each step in the process successfully the first time through to prevent delays. The best way to make sure you are prepared is to conduct one or more internal EVMS Mock Reviews, the topic for the next blog.
EVMS Compliance Review Series #2 – Conducting Internal Mock Reviews (Self Assessments). This blog discusses the importance of conducting a thorough internal review of your EVMS. You may or may not have the expertise in-house to conduct this simulation of a Compliance Review. An independent third party can help you prepare for a DCMA compliance review. The objective is to conduct the EVMS Mock Review to simulate everything DCMA will do. DCMA also expects a thorough scrub of the schedule and cost data – data traceability and integrity is essential.
EVMS Compliance Review Series #3 – Using Storyboards to Depict the Entire EVMS. Do you need a refresher on the role of storyboards in a compliance review? Storyboards can make a difference in training your personnel and explaining to the DCMA personnel how your EVMS works. Storyboards can take many forms, and if you don’t have one in place, consider starting with the flow diagrams in your EVM System Description.
EVMS Compliance Review Series #4 – Training to Prepare for Interviews. This blog highlights the importance of conducting training for your personnel, particularly the control account managers (CAMs), so they are able to complete successful interviews with DCMA personnel. H&A recommends completing a three step training process to proactively address any issues.
Help Preparing for a Compliance Review
Do you need help preparing for a DCMA compliance or surveillance review? Download the set of DCMA Business Practices and read our updated blogs so you have an idea of what is ahead. Humphreys & Associates can help you conduct a Mock EVMS Review, perform a data quality assessment, create a storyboard, or conduct EVMS interview training and mentoring for your personnel. Call us today at (714) 685-1730 or email us.
One of the Earned Value Management (EVM) topics that always initiates lively debate is the planning of Scrap, Rework, and Repair (SRR). These debates often become very emotional. So, what makes the topic of planning SRR so emotional? There are two primary factors. First, you are planning for something that is not in alignment with a success oriented plan. In an ideal project there would be no Scrap, Rework, or Repair. Second, we do not know what parts will require SRR or when it will occur. Let’s start with baselining some definitions:
Scrap – Manufactured articles or parts that are rejected or discarded. Waste that either has no economic value or only the value of its basic material content. Examples include a part that was made too small or a part that was damaged and could not be repaired.
Rework – The process of bringing a non-conforming part back into conformance by re-performing a previous process step. An example would be a part with a hole that was drilled undersize that could be re-drilled to the correct size.
Repair – The process of bringing a non-conforming part back into conformance by using a process outside the original process. An example would be a part that was painted and the undersized hole was not discovered until after it was painted. The repair now requires additional process steps, of stripping and re-preparing the material, that were not part of the original process. (Note: for this discussion we will focus on inline repairs. Repairs that arise post acceptance are not included in this discussion.)
Along with these basic definitions, we need to understand how your company defines and handles these costs. Some companies treat these costs as indirect and some treat them as direct costs. When these costs are classified as indirect costs, the company establishes material overhead pool(s) that collect the costs for allocation across the direct material dollars. These pools might be segregated by material type and have different allocation bases. A company’s CASB Disclosure Statement will define the pools and bases. Some companies treat these as direct charge items and will have procedures for the treatment of SRR and non-conforming material costs. RULE 1 – The budgeting of SRR must be consistent with the way costs are collected and charged. Because of the vagueness of knowing what parts will require SRR and when it will occur, the indirect costing approach is the most straight forward method within an Earned Value Management System (EVMS).
Next we need to understand how your company’s shop floor works and how non-conforming material is handled. Most shop floors work with shop orders that are issued to direct how parts are processed and routed through the process. As a part is processed into a higher level part or subassembly the costs are usually collected at that next level part/subassembly. In this way each part’s cost can be established by summarizing all the lower level parts and routing steps. In an EVMS, these shop orders are usually grouped into work packages. Usually the shop floor has procedures in place to identify the cause and corrective action associated with an issue when a part is identified as non-conforming. The corrective action approach will define what will have to be done to resolve the issue. The corrective action can be anything: scrapping and starting over from an earlier process step with an updated procedure, re-procuring, repairing, or reworking. In any corrective action approach, new procurement request(s) and/or shop order(s) will be issued with new direction. The costs are then collected and handled based on how your company has defined the process. Most companies have an additional requirement to segregate these costs to support their Cost of Quality program/system. (We could dive deeper into the processes for each scenario, but that is not the focus of this blog.)
Now that we have some basic understanding of what SRR is, how it is handled on the shop floor, and how it is costed, we can look at how to budget it in an EVM environment. Remember, we do not know what parts will need SRR, and for those that will need SRR, we do not know when it will be needed.
Let’s take the indirect costing approach first. The budget for SRR is established by the overhead factor being applied to the base cost. The value of the overhead rate is determined based on the annual planning process. As a dollar of the base material pool is planned, the SRR rate is applied. An owner is established for each pool that will also be the source for future variance analyses and forecasts.
For the direct costing approach there are several options. The following are the most common planning and budgeting options used:
Control Accounts with Planning Packages
Summary Level Planning Packages
Management Reserve
Unplanned SRR
The first 3 options have an amount of SRR that has been identified either as a factor based on historic data or as part of the Risk Management process. This SRR is usually identified to an assembly, sub-assembly, or part. The fourth option addresses an SRR event that was not planned in the baseline.
The first option is to include SRR in the Scope of Work for the production Control Account(s). The CAM then establishes one or more planning packages for SRR. The planning package(s) are associated with a grouping of parts and/or timing for effort in the future beyond the detailed planning horizon. As SRR is identified, the planning package is detailed planned (partially or in its entirety) into a work package. The procurement directions and/or shop orders that make up the non-conforming corrective action are grouped to make up the work package. In this approach it is possible that the conversion from planning packages to work packages will occur in the current accounting period; note that this approach might be in violation of a company’s defined freeze period procedure. When there is enough insight into the items identified as possible SRR candidates, including the timing of the SRR, a budget will be pulled from the planning package into a work package as part of the normal rolling wave planning cycle. The goal always should be to plan the effort into work packages as early as enough information is available. In this scenario the CAM will assess performance, perform variance analyses, and provide forecasts.
The second option is to budget a Summary Level Planning Package (SLPP) at a WBS level higher than the Control Accounts. This approach is used when SRR is planned for a WBS element but the specific Control Account cannot be identified. This budgeting approach works similar to converting from planning packages to work packages, but there are additional steps to authorize and issue scope and budget from the SLPP to the CA. The Program Manager, Integrated Product Team Lead, or WBS Element Manager will provide forecasts for the SLPP as part of the EAC process.
The third option is for the Program Manager to hold the budget for SRR in Management Reserve (MR). As SRR is identified, the CAM will request MR using the normal change control process. The PM will address the MR when analyzing the program’s overall performance.
The fourth option addresses how to handle unplanned SRR. Often these approaches of creating new Work Packages and making Earned Value adjustments may “violate one or more EVMS rules” but pass the cost/benefit common sense rule. In this option the new procurement direction and/or shop orders are added to the existing work package grouping. There is no new budget allocated and the additional actual costs that are collected are explained as a variance. If that work package had been closed it will need to be re-opened. If cumulative BCWP is now overstated, it may need to be adjusted (de-earned) to reflect that work is still remaining. The ETC/EAC is also updated to reflect the estimated timing and cost for the SRR. If you select this approach, make sure your system description and procedures allow for these exceptions to generally accepted rules. This approach may drive numerous anomalies in the EVM data, which will need to be explained in Format 5 of the Contract Performance Report or Integrated Program Management Report.
If the SRR is a large amount of work and will take a significant amount of time, it might warrant establishing an Over Target Baseline/Schedule (OTB/OTS). If this is the case, be sure to discuss the approach with your customer.
Additional Cautionary Tales and Lessons Learned:
Cost versus Benefit – Make sure that your manufacturing system can support what is described in your EVM System Description. Also, understand the cost impact for the process benefits that you are designing. Sometimes the benefit does not justify the cost.
Understand how your manufacturing and accounting systems handle scrap, rework, and repair. These are the source systems that will drive how you handle SRR for Earned Value Management.
Material and Labor Cost in the Same Work Packages – If the part that requires repair or rework was a buy item, it was budgeted as material. The repair or rework may appear as labor. Some systems restrict the comingling of production material and labor in the same work packages. In the case of SRR that restriction should not apply.
Purchasing Clauses – Ensure that SRR and the associated costs are adequately addressed in purchasing clauses for buy parts. Also, make sure you understand how major subcontractors with an EVMS flowdown requirement handle SRR in their systems.
Fast Tracking increases the risk of SRR – Starting Low Rate Initial Production prior to completing the design and development effort will lead to starting production with a dynamic technical data package. This increase in risk will also increase the amount of SRR that can be expected on a project.
SRR outside the shop floor – There are similar issues that need to be addressed when performing Software, Integration, Spares, Tooling, and Testing efforts.
Make sure your system description reflects how you handle the budgeting, earning, estimating, and costing of SRR.
We only addressed the topic of BUDGETING Scrap, Rework, and Repair at a summary level in this blog. The devil is always in the details. We recommend that you test your approach in your systems prior to implementing to ensure your tools operate as you expect. If your EVMS is validated through the DCMA, or other validating/certifying agencies, you should seek their approval of your procedures prior to implementation. Also, the Integrated Master Schedule (IMS) process and Risk/Opportunity Management System need to address SRR.